Difficult business loans in Australia: when a bank or cash-flow lender has said no
A difficult business loan is one the usual lender will not write because of defaults, an ATO debt, irregular cash flow, no financials or a deadline. HomeSec lends from $20,000 to $5,000,000 against equity in real estate, so the test is the property, the purpose and the exit. First and second mortgages can fund in as little as 24 hours from a clean, complete scenario.
"Difficult" is the word business owners use after a bank or an online lender has turned them
down. It rarely describes the business. It describes the lender's rules, and the same loan that fails
one lender's test passes another's, because the two are testing different things. This page sets out
what makes a loan difficult, what a property-secured lender looks at instead, and where to read the
detail on each problem.
Seven reasons a loan becomes difficult
Almost every refusal falls into one of seven groups. For each, the usual lender is testing something
the business cannot show, and a lender that lends against real estate is testing something it can.
Every application is subject to assessment and approval. Credit provided for those purposes is not regulated under the National Consumer Credit Protection Act 2009 (the NCCP Act), and the protections available to consumer borrowers do not apply.
Why cash-flow lenders and banks say no
A bank tests serviceability: can the business's income cover the repayments, shown by financials and tax
returns, over a process that takes weeks. An online cash-flow lender tests turnover and bank statements,
fast, by algorithm, and says no the moment the recent months look thin. Neither looks at the property the
owner holds, and for an owner with equity in real estate that is the strongest thing they have.
Our guide to cash-flow lenders compared sets out how the two kinds differ, and
declined by a cash-flow lender covers what to do next.
When cash-flow lenders say no, equity is the answer
If the client has real estate security, or equity in it, the loan is no longer difficult. It becomes
a question of how much equity there is and what the money is for. A second mortgage
registers behind the existing bank loan and leaves it untouched; a
first mortgage pays the existing lender out; a
caveat loan is the quicker of the three where the first lender is slow.
Interest can be capitalised for up to six months, so there can be no repayments for up to the first six months
while the business recovers, and the term is open, so there is no date set by the lender.
Examples of difficult loans we have funded
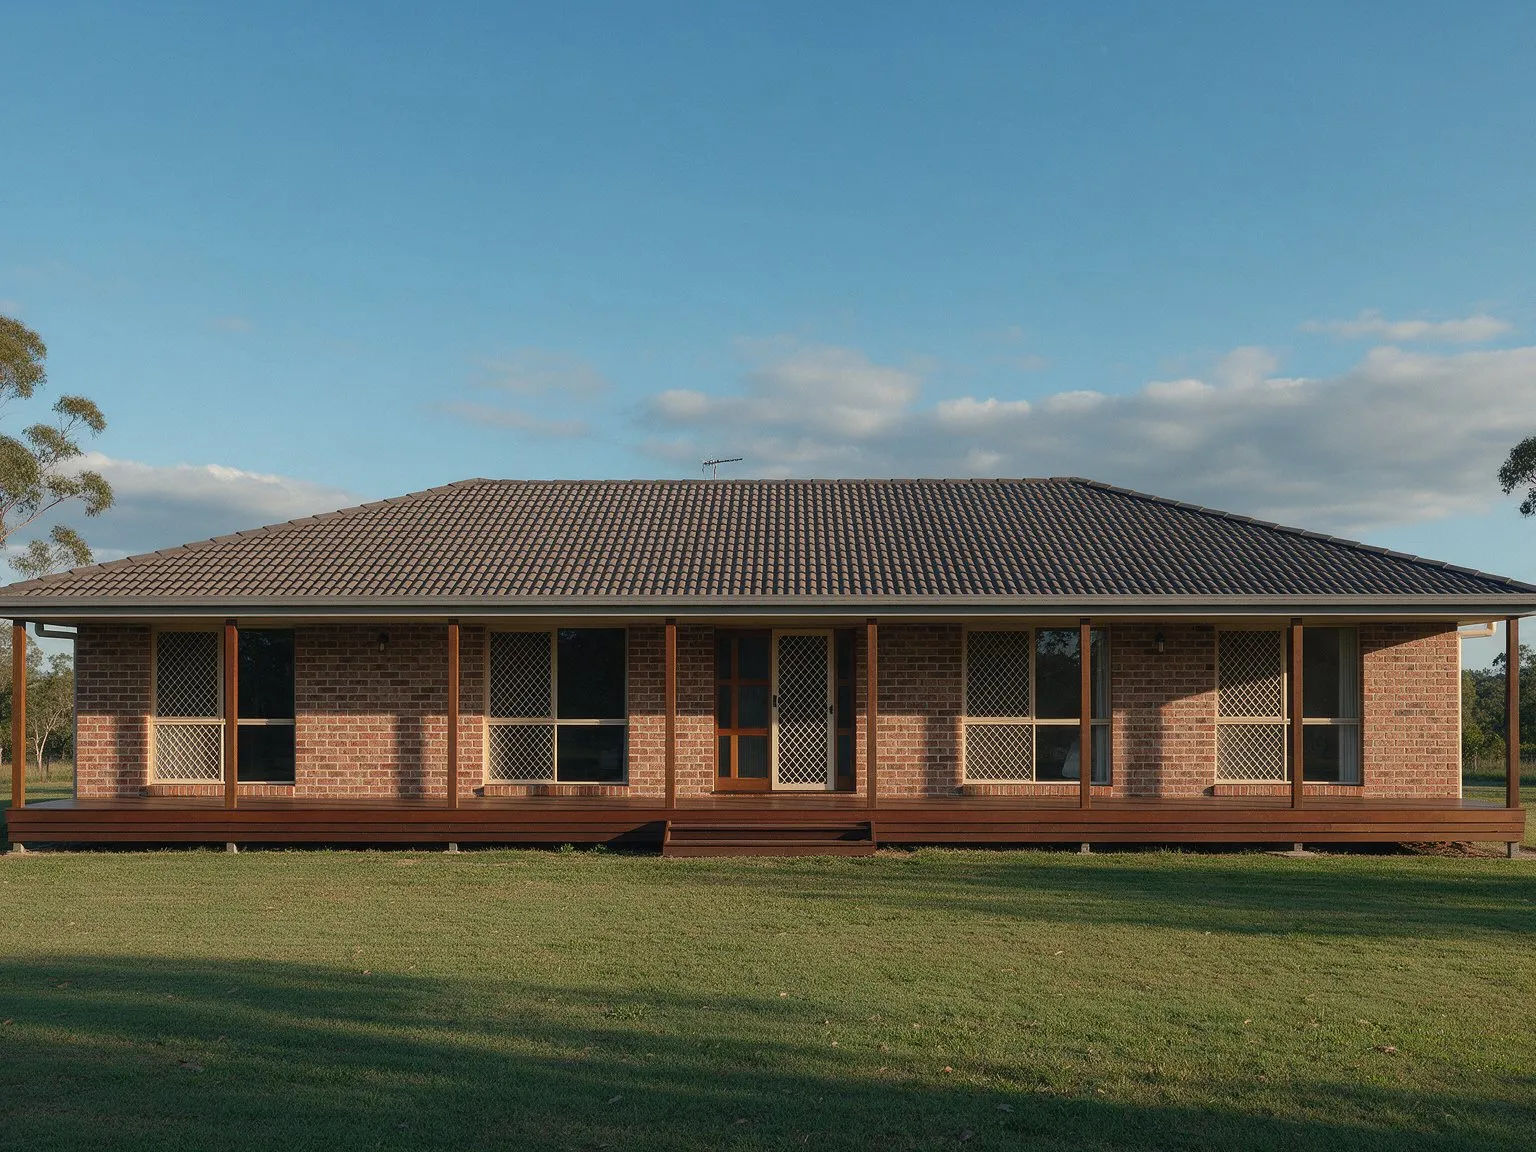
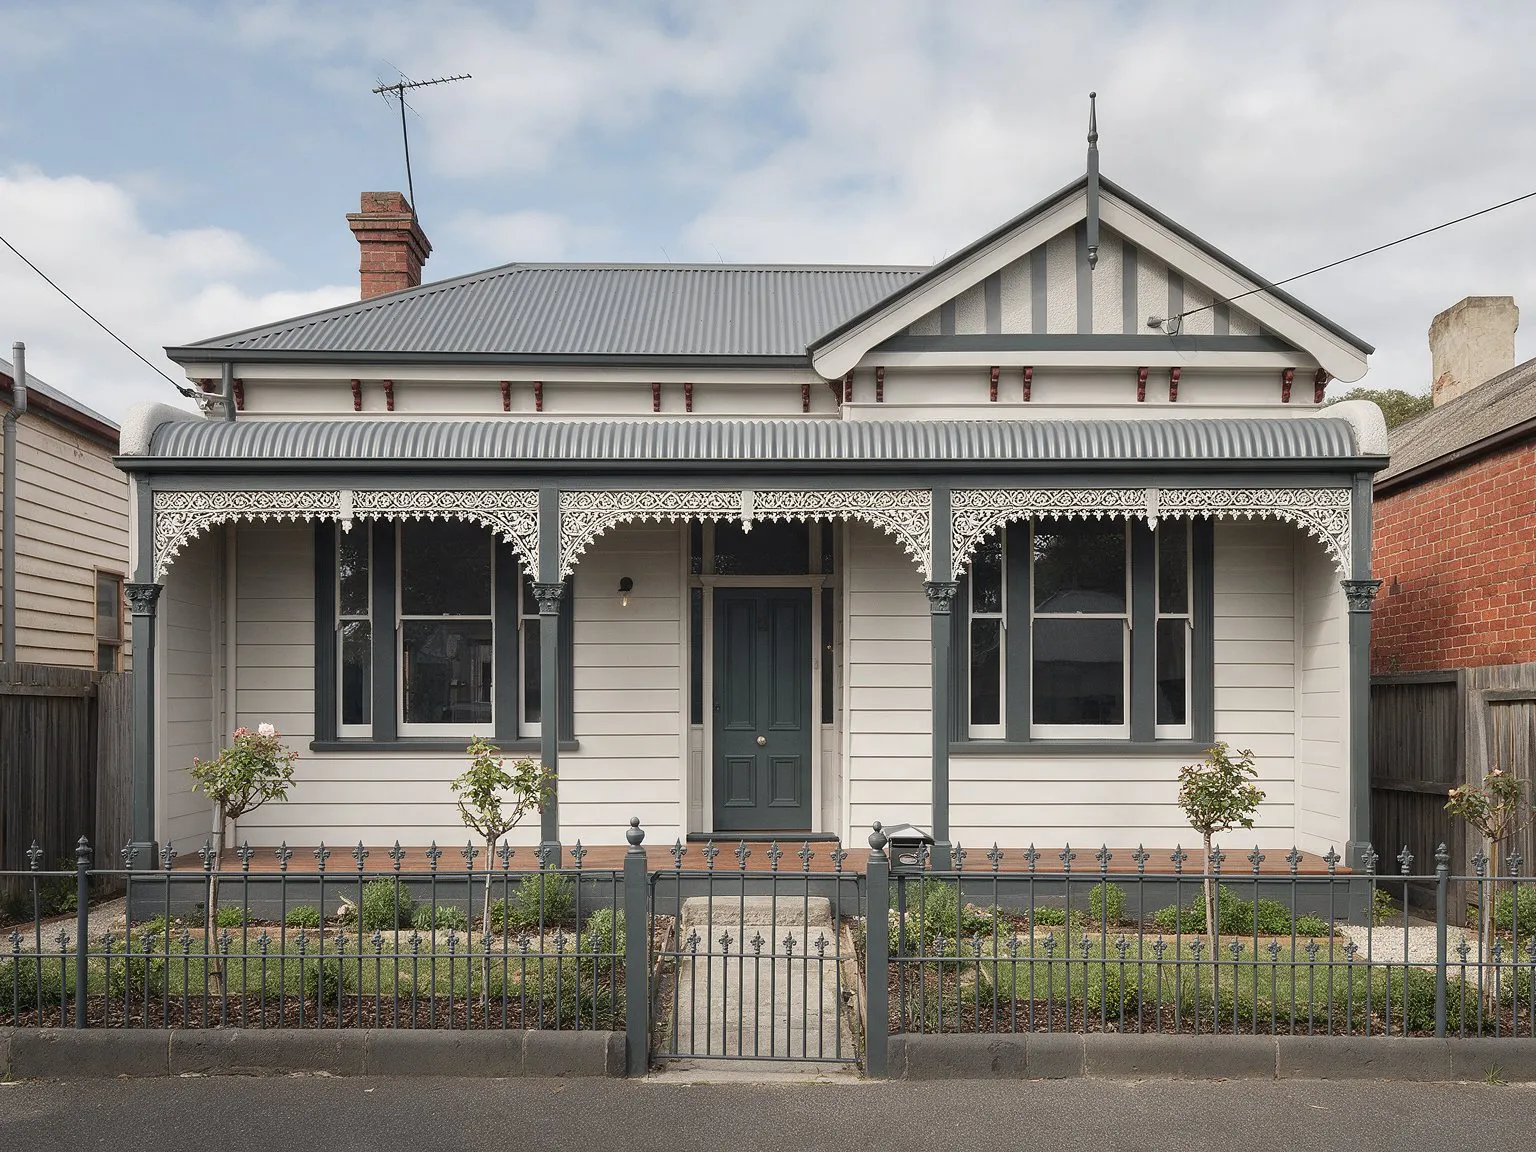
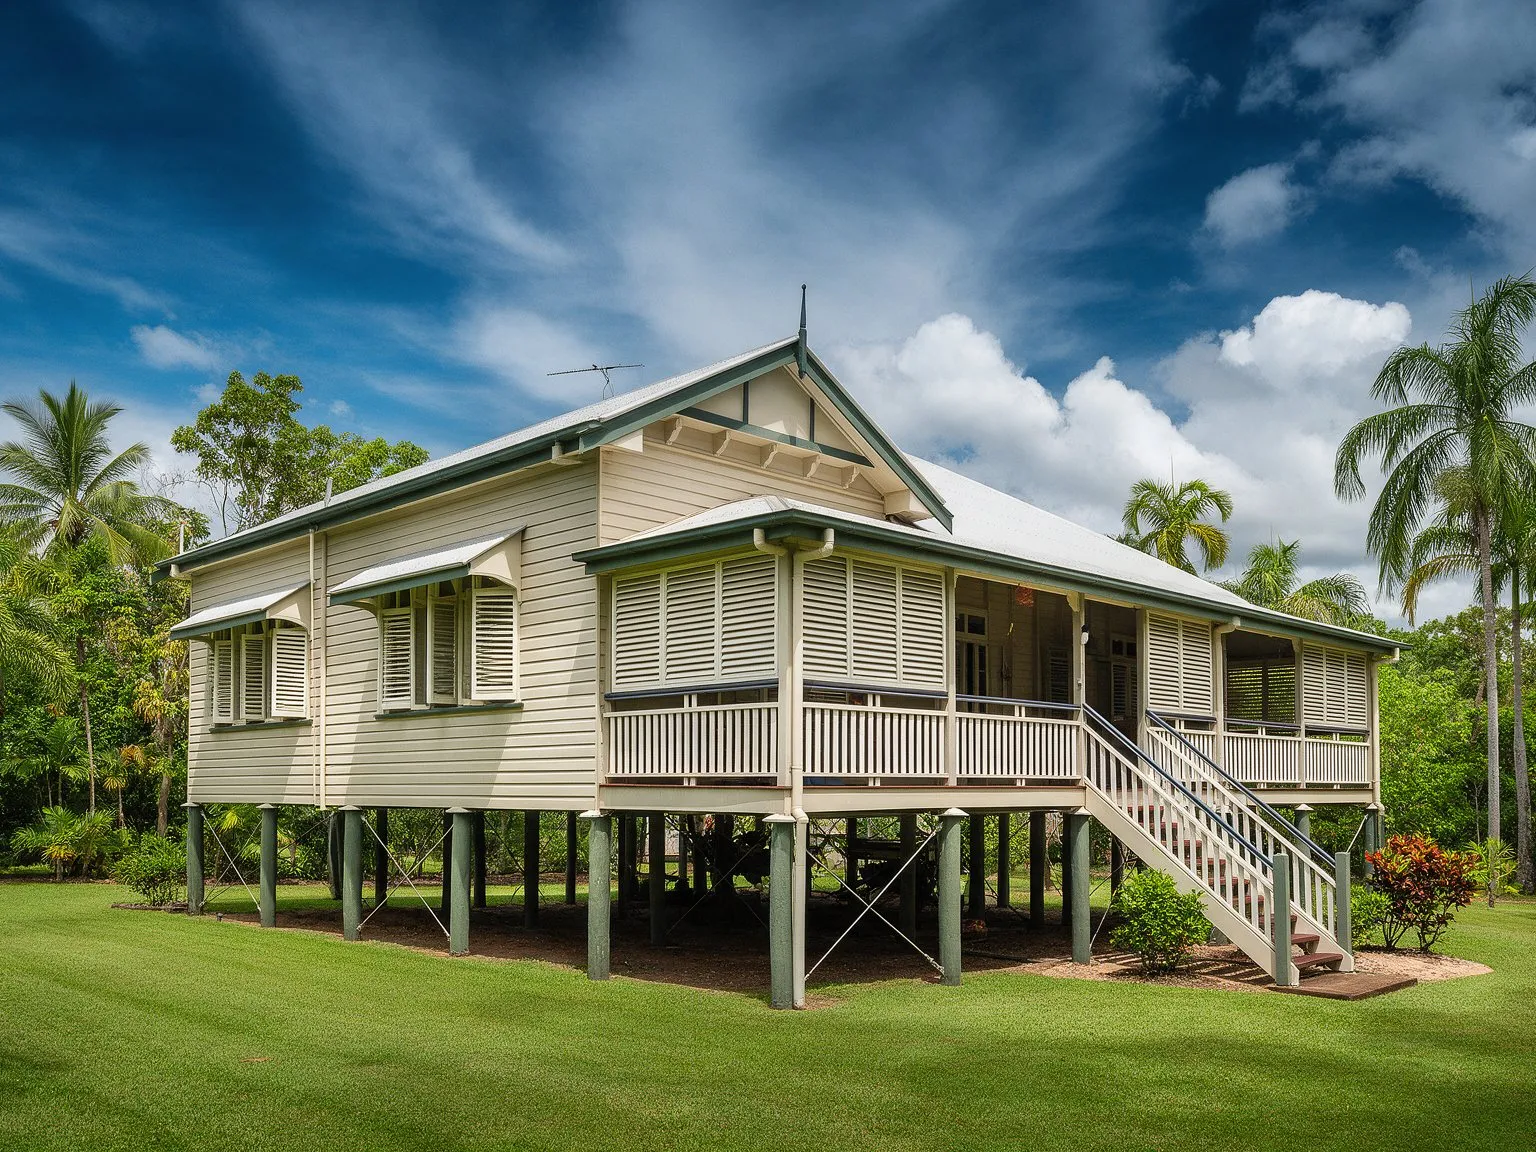
Each of these is modelled on a loan we settled in the month shown. The client, suburb, property and
figures are changed to protect clients, and the photograph is a representative image.
Second mortgageFunded October 2026
Yandina, QLD
Refinance business cash-flow debts
$300,000 against a $1,150,000 property · 63.5% combined LVR · 6 months
Two cash-flow lenders had said no because the business's last few months of bank statements looked thin. The directors owned their home with plenty of equity. We registered a second mortgage behind the existing bank loan, left that loan exactly where it was, and capitalised the interest for the term so nothing was payable while the business recovered.
First mortgageFunded October 2026
Brunswick, VIC
Pay out a lender in arrears and an ATO payment plan
$700,000 against a $1,350,000 property · 51.9% combined LVR · 12 months
A non-bank lender had issued default notices over the property and the company had fallen behind on an ATO payment plan at the same time. One first mortgage paid out the arrears loan and the ATO balance in a single settlement, so two pressures became one lender and one repayment plan, with a refinance to a bank as the exit.
Second mortgageFunded September 2026
Palmerston, NT
Stock and staffing ahead of the peak trading season
$200,000 against a $980,000 property · 59.2% combined LVR · 6 months
The owner of a hospitality business needed stock and staff in place before the dry-season peak, and the bank's overdraft review was weeks away. A second mortgage behind the existing home loan put the working capital in hand before the season opened, and the sale of the season's trade was the plan for repaying it.
We can lend $20,000 to $5,000,000 against residential, commercial and rural property anywhere in Australia, to companies, trusts and sole traders, including start-ups.
We cannot write unsecured loans, fund construction, provide invoice finance, or lend to buy or refinance a home to live in.
We will tell you early if the property does not carry enough equity, rather than after a week of paperwork.
How to start
Tell us the property, what is owing on it and what the money is for. The application is
three short questions, with no credit check to apply and no financial statements. Check
business loan eligibility first if you want to see the limits, or call
us on the number in the page header.
If a bank or a cash-flow lender has already said no, the question is whether the property you own can say yes.
If you are reading this because money is tight, it may be that what you actually need is fast business finance — and HomeSec can lend with very few qualification criteria. All you need is sufficient equity in real estate and a business purpose: no financials, no valuation, no credit score threshold, funded in as little as 24 hours from a clean, complete scenario. Best of all, the first six months can come with no requirement to make any payment.
That's the HomeSec Advantage.
Questions people ask alongside this one
What is a difficult business loan?
A difficult business loan is one the usual lender will not write: the business has defaults, an ATO debt, irregular cash flow or no financial statements, the borrower is a start-up or a discharged bankrupt, or the money is needed faster than a bank can move. The loan is difficult for that lender's rules, not for the business. A lender that tests the property instead can often write the same loan.
Why do banks and cash-flow lenders decline business loans?
Because both test the business's own numbers: turnover, recent bank statements, financials and a credit score. A bank adds serviceability and time; an online cash-flow lender adds an algorithm. A business with thin recent statements, a tax debt or a default fails the test whatever the property it owns is worth.
Can I get a business loan with bad credit or an ATO debt?
Not a barrier to applying. HomeSec lends against property, so there are no financial statements to apply and no credit check to apply. Read no doc business loans for what we ask instead.
How fast can a difficult loan be funded?
As little as 24 hours from a clean, complete scenario; the usual range is 24 – 72 hours. Every application is subject to assessment and approval.
What security do you need?
Real estate: residential, commercial or rural property with equity in it, anywhere in Australia, up to 80% LVR on residential and 70% on commercial. A second mortgage sits behind the existing bank loan; a first mortgage pays it out.
What can't you help with?
Unsecured business loans, construction, invoice finance, and loans to buy or refinance a home to live in. If the property does not carry enough equity, we will tell you in the first conversation rather than after you have spent a week on it.
Sixty seconds, no documents
See if you qualify in sixty seconds
Three short questions, no credit check to apply and no financial statements. A Lending Manager reads it and calls you back with a real answer — not a call centre, not an algorithm.