
Fast & Flexible Business Loans $20,000 to $5,000,000 with no payments for the first six months
That's the HomeSec Advantage.
Australia's private business lender since 2004 — funding our own loans, with our own money, and answering our own phone. No financials. No valuations. No repayments for six months.
Live rating, pulled from Trustpilot. We reply to negative reviews as well as positive ones.
From a small equity release to a large funding line — one credit team, one decision.
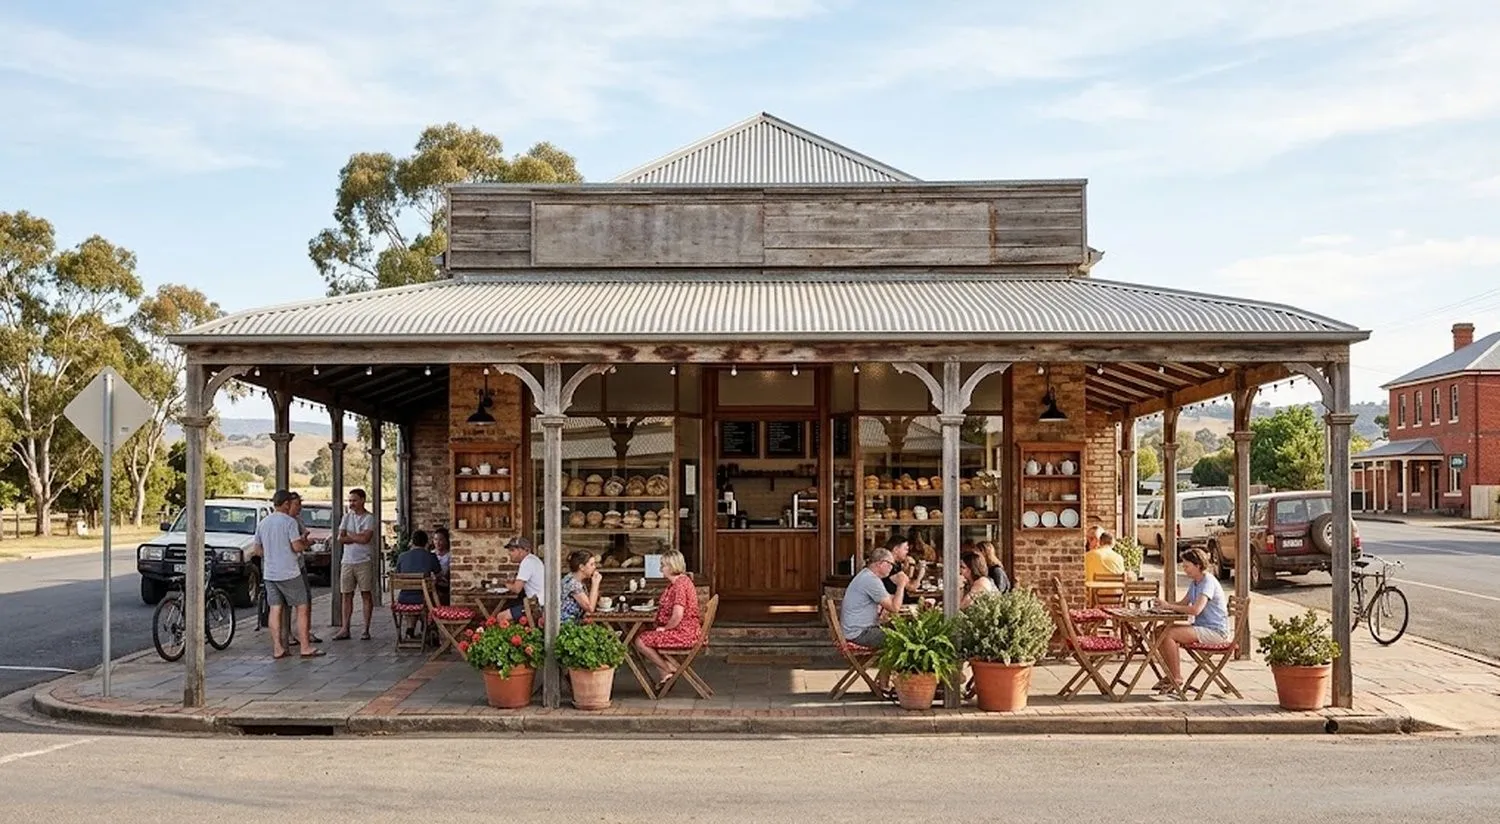
Whatever brought you here, the question is the same. Is there equity, and is there a reason?
These are the six situations we fund most. If yours looks close, it is worth a phone call — the edge cases are usually the ones worth a conversation.
The bank said no. The ATO said now.
Tax or creditor pressure, and equity sitting in your home or an investment property that the bank will not let you reach in time.
How we fund it → OpportunityStock, plant or a site at a price
A window that closes in days, not in the six weeks a bank needs to reach an answer. The deal is good; the timing is the problem.
How we fund it → BridgeA settlement or refinance that moved
The exit is already in sight — a sale, a refinance, money that is coming — just not yet. You need to get from here to there.
How we fund it → Start-upNo trading history at all
New entity, new ABN, no financials to show anyone. Equity in property and a clear purpose carry the case.
How we fund it → Credit-impairedDefaults, arrears, a thin file
A credit score that rules you out everywhere else does not rule you out here. We lend against the property and the exit.
How we fund it → RegionalOutside the metro postcodes
A country town, a rural holding, vacant land — security that a capital-city lender will not look at.
How we fund it →No real-estate security to offer, a loan that would sit third behind two existing mortgages, or money for personal or domestic purposes — those are not HomeSec loans, and we will tell you inside the first phone call rather than three weeks in.
Six ways to turn property equity into working capital
Every HomeSec loan is secured by real estate — residential, commercial, industrial, rural or vacant land. What changes is where we sit on the title, and how fast we can get there.
Caveat Loans
A caveat over property you already own. The fastest instrument we have, and the one that does not need your existing lender's consent.
- Amount
- $20k – $5M
- Term
- Open — you choose
- Settlement
- 24 hours
Second Mortgage Business Loans
We sit behind your existing bank. Your low home-loan rate stays exactly where it is — nothing to refinance, no break costs.
- Amount
- $20k – $5M
- Combined LVR
- to 80%
- Settlement
- 24 – 72 hrs
First Mortgage Business Loans
First position on the title — over a property you own outright, or by paying out your existing lender on the day we settle.
- Amount
- $20k – $5M
- LVR
- to 80%
- Consent needed
- None
Business Bridging Loans
The gap between one certainty and another: a settlement that moved, a refinance that stalled, a claim certified but not yet paid.
- Amount
- $20k – $5M
- Repayments
- none, 6 mths
- Exit
- sale or refinance
No Doc Business Loans
No tax returns, no BAS, no valuation. Assessed on the property and a credible exit, by a person, not on the last two years of trading.
- Amount
- $20k – $5M
- Financials
- Not required
- Settlement
- 24 hours
ATO & Tax Debt Funding
Clear the ATO in full, stop the interest clock, and close out a Director Penalty Notice before it becomes a personal liability.
- Amount
- $20k – $5M
- Paid
- direct to ATO
- Settlement
- 24 hours
Three steps. An answer in minutes, approval in about fifteen, funding in as little as 24 hours.
No application portal to fight, no document checklist that runs to two pages, and no waiting on a valuer. This is the whole process.
Tell us the deal
Amount, purpose, timing, the property and how the loan gets repaid. A Lending Manager gives you an indicative answer on that call — usually in minutes.
Minutes
Conditional approval
Photo ID, a rates notice and your most recent mortgage statement. That is the whole list, and it takes about fifteen minutes.
About 15 minutes
Funds released
As little as 24 hours from a clean, complete scenario. Paid where you tell us — to your account, or straight to the ATO.
As little as 24 hours
Seven things to have ready when you call.
Tell a Lending Manager these seven, and you will usually have an indicative yes or no before you hang up. None of them needs a document.
- 1What the security property is roughly worthYour own estimate is fine — we assess value ourselves, so there is no valuation to arrange.
- 2The property's addressWe run the title search. You don't need to supply anything.
- 3What is owing on it, and to whomThis is what decides whether we sit first or second, and how much equity is available.
- 4How much you want to borrowAnywhere from $20,000 to $5,000,000.
- 5How long you want it forFrom one month. There is no maximum, and you can extend or repay early.
- 6How many people are on the titleEveryone on title signs, so we need to know who is involved from the start.
- 7What the money is forThe business purpose. It is the one thing that has to be there.

A person decides every loan. No AI, no scorecard.
Every application is read by a Lending Manager and every credit decision is signed off by a person. We do not use artificial intelligence to assess, approve, decline or price a loan.
An algorithm cannot see why the last two years look the way they do. A person can, and that is the whole reason files we write are ones a scorecard would have rejected.
Every industry, at every size — the common thread is the property, not the trade.
We have funded sole traders with one ute and companies with forty staff. What decides it is equity in real estate and a reason the bank's timetable does not work, not the ANZSIC code on your ABN.
Most private lenders broker your file to someone else. We fund our own loans, with our own money.
That is not a slogan — it is the reason we can give you an answer on the first phone call instead of "let me check with the funder". Since 2004. Through two recessions, a mining downturn, a pandemic and a construction shakeout.
Open-ended funding secured by property you already own. No fixed end date. No daily debits. No serviceability test.
Mon–Fri, 8:30am – 5:30pm Melbourne time. A Lending Manager, not a call centre.