
Most private lenders stop at the capital cities. We don't
HomeSec funds loans secured by real estate across every state and territory — metropolitan, regional and rural residential. One credit team in Melbourne, a local landline in nine cities, and a willingness to look at security that metro-only lenders won't.
HomeSec lends in every Australian state and territory, city and country, from $20,000 to $5,000,000 secured by residential, commercial, rural or vacant land. Towns of 3,000 or more people are in scope as a guide, smaller on merit, and one credit team in Melbourne assesses every file — so the answer is the same in Bundaberg as in Brisbane.
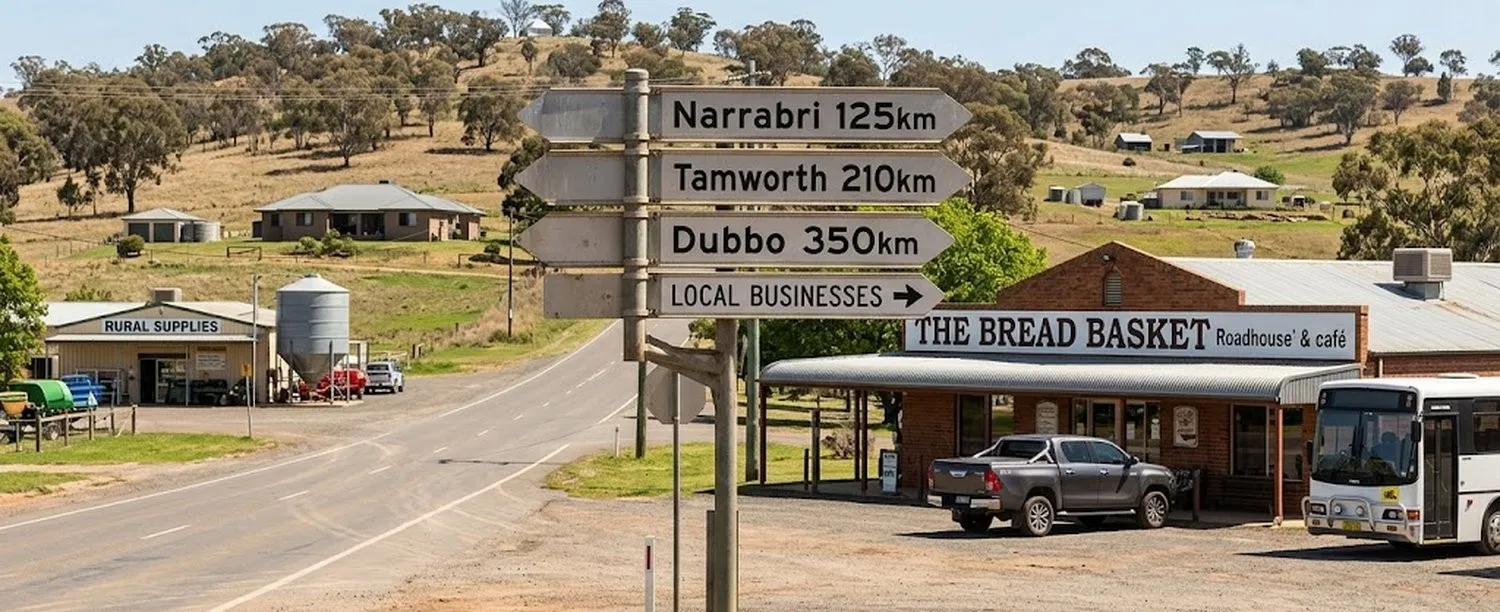
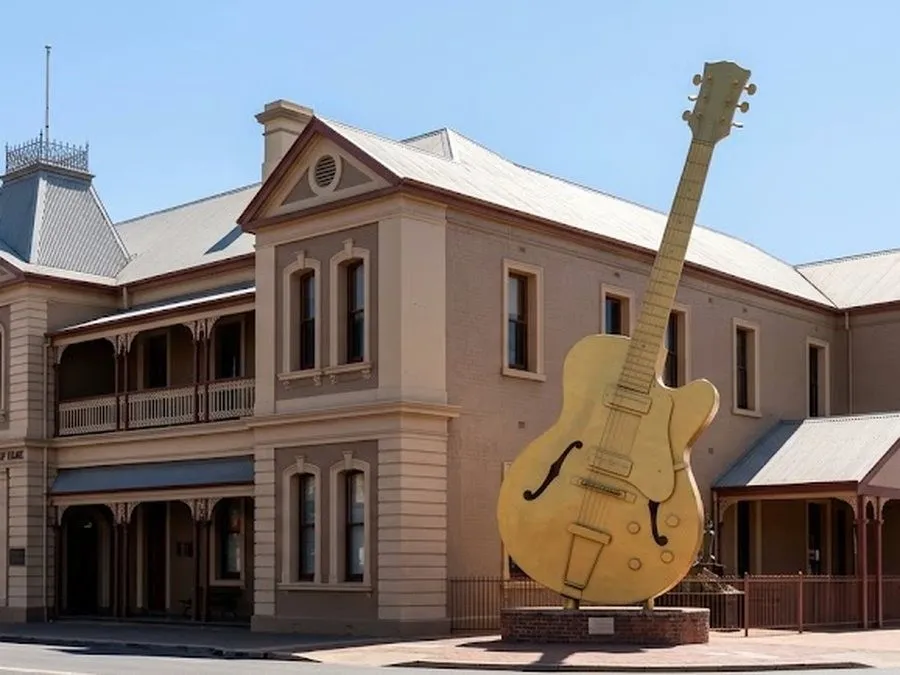
Country towns are core business, not an exception.
Almost any residential property in a town of 3,000 or more people is in scope, with smaller populations and commercial security considered on merit. Rural property, vacant land and mixed-use security all have a home here.
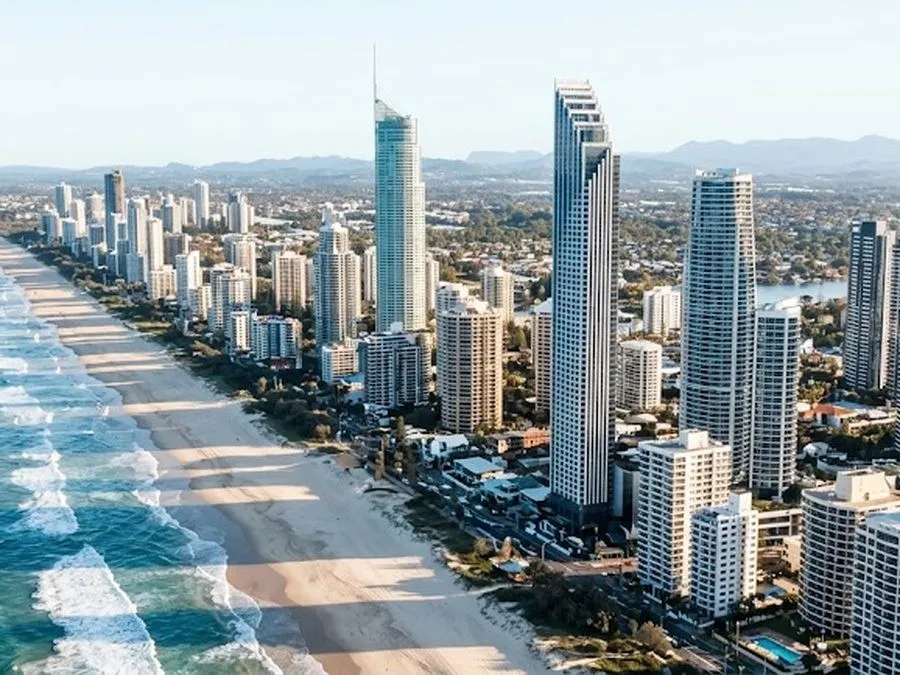
And every capital city and major centre.
Sydney, Melbourne, Brisbane, Perth, Adelaide, the Gold Coast, Hobart, Canberra and the major regional centres in between — the same equity-led assessment and the same funding in as little as 24 hours apply everywhere.
Declined because of your postcode? That is a metro-lender problem, not a you problem.
Most private lenders restrict themselves to the capital cities — some explicitly, some by quietly declining anything more than an hour from a CBD. If you run a business in Wagga, Bundaberg, Mount Gambier or Kalgoorlie and you have equity in property, you have almost certainly been told no by someone who never looked at the file.
We look at the security, not the postcode. Regional and rural residential property is a normal part of our book and has been since 2004. There are limits, and we will tell you honestly what they are on the first call rather than after you have paid for something — but "it's regional" is not by itself a reason we decline.
What changes when the property is a long way from a capital
One thing, really: how long the property would take to sell if it came to that. Every line below is a consequence of it, and none of them is a reason to decline on its own.
| Security | How it is assessed |
|---|---|
| Town size | Towns of 3,000 or more people as a guide; smaller populations on merit. |
| LVR | Up to 80% on residential and 70% on commercial. Lower on large acreage, and LVRs may reduce on properties worth less than $800,000. |
| Rural and acreage | Lifestyle blocks and working farms are both considered. The larger the holding, the lower the LVR, because the buyer pool is smaller and the sale period longer. |
| Vacant land | Accepted, at a lower LVR than an improved property. Zoning and services matter more than the postcode. |
| Commercial in a small town | On merit. A tenanted shop on the main street of a regional centre is one thing; a specialised premises in a town of 1,500 is another, and we will say which on the first call. |
| Mining and single-industry towns | Considered, with the LVR reflecting how exposed the local market is to one employer. We have written enough of them to know which markets move. |
| Valuation | None. We assess the property ourselves, and where we want a local view we instruct a market appraisal from an agent in the town, which does not add a week the way a sworn valuation does. |
Call your local number
Nine local landlines. One credit team. Same answer, same day.
Every one of these rings the same credit team in Knoxfield. We do not pretend otherwise, and the person who answers will tell you where they are sitting. That is a stronger position than the alternative, because it is the reason the answer comes so fast: one team, one set of files, nobody waiting on a branch to call head office back.
States & territories
Each state below carries the one thing that genuinely differs by jurisdiction: which registry your security is lodged with, how long that takes, and what changes outside the metro area. A caveat loan in Melbourne versus Geelong involves identical mechanics. A caveat loan in Victoria versus Queensland does not.
Victoria
Home state. Credit team, office and settlement solicitors all here — Victorian files are typically the fastest we write.
- Registry
- Land Use Victoria
- Typical
- 24 – 48 hours
New South Wales
Largest state by volume. Two local numbers, Sydney and Newcastle, and we lend well beyond both — Hunter, Illawarra, Central West, Riverina.
- Registry
- NSW Land Registry Services
- Typical
- 24 – 48 hours
Queensland
Brisbane and Gold Coast numbers, plus regional coverage north through the coastal centres — Sunshine Coast, Toowoomba, Cairns, Townsville.
- Registry
- Titles Queensland
- Typical
- 24 – 48 hours
Western Australia
The time difference works in your favour: WA files signed after lunch local usually fund next morning east-coast time. Bunbury, Geraldton, Albany.
- Registry
- Landgate
- Typical
- 24 – 48 hours
South Australia
Adelaide metro and the major regional centres — Mount Gambier, Whyalla, Port Lincoln.
- Registry
- Land Services SA
- Typical
- 24 – 48 hours
Tasmania
The Hobart number covers the state, Launceston, Devonport and the north-west included.
- Registry
- Land Titles Office via LIST
- Typical
- 24 – 48 hours
Australian Capital Territory
Note the Territory's Crown leasehold system — routine for us, but worth raising on the first call.
- Registry
- ACT Land Titles
- Typical
- 24 – 48 hours
Northern Territory
Darwin, Palmerston and Alice Springs. No local number here yet — the national line covers it.
- Registry
- NT Land Titles Office
- Typical
- 24 – 48 hours
Questions about where we lend
Does HomeSec lend in regional Australia?
Which states do you lend in?
Do I have to come to an office?
Will you lend against a farm or a rural property?
What about vacant land?
I was declined because of my postcode. Will that happen here?
Is a loan in Western Australia or Queensland slower than one in Victoria?
Do you lend in the Northern Territory?
Where we actually are
One office, one credit team, nine local numbers — and we would rather say exactly that than imply a branch network we do not have. Every loan in every state is assessed by the same people at the same address.
- Head office
- Level 1, Suite 6, 1488 Ferntree Gully Road
Knoxfield VIC 3180 - National line
- 1300 93 83 87
- Hours
- Mon–Fri, 8:30am – 5:30pm Melbourne time
Level 1, Suite 6, 1488 Ferntree Gully Road, Knoxfield VIC 3180. One office, and every file in every state is assessed from it.
See if you qualify in sixty seconds
Three short questions, no credit check to apply and no financial statements. A Lending Manager reads it and calls you back with a real answer — not a call centre, not an algorithm.
That's the HomeSec Advantage.
The same loans in every state and territory.