
Funding our own loans since 2004 $20,000 to $5,000,000 Funded in as little as 24 hours No repayments for 6 months
HomeSec Business Finance
Examples · August 2026 to October 2026

Recent first and second mortgage business loans we have funded

These are 10 recent first and second mortgage business loans HomeSec settled between August 2026 and October 2026, from $150,000 to $1,450,000, across 8 states and territories. Each shows the property value, what was owing, what we lent, the combined LVR, the term and the business purpose. Details are changed to protect clients.

5 are second mortgages and 5 are first mortgages; 4 are over regional or rural property. On any of them interest can be capitalised for up to six months, which means no repayments for up to the first six months.

Have a property with equity and a business that needs money? Tell us the property and the purpose.

See if you qualify
What these examples are

Each card is modelled on a loan we settled in the month shown. To protect our clients we change the suburb, the property and the figures, and the photograph is a representative image, not the actual property. We have not used client names, and nothing here is a testimonial or a promise of the same terms: every application is subject to assessment and approval. We do not fund construction, and we do not lend to buy a home to live in.

Funded in October 2026

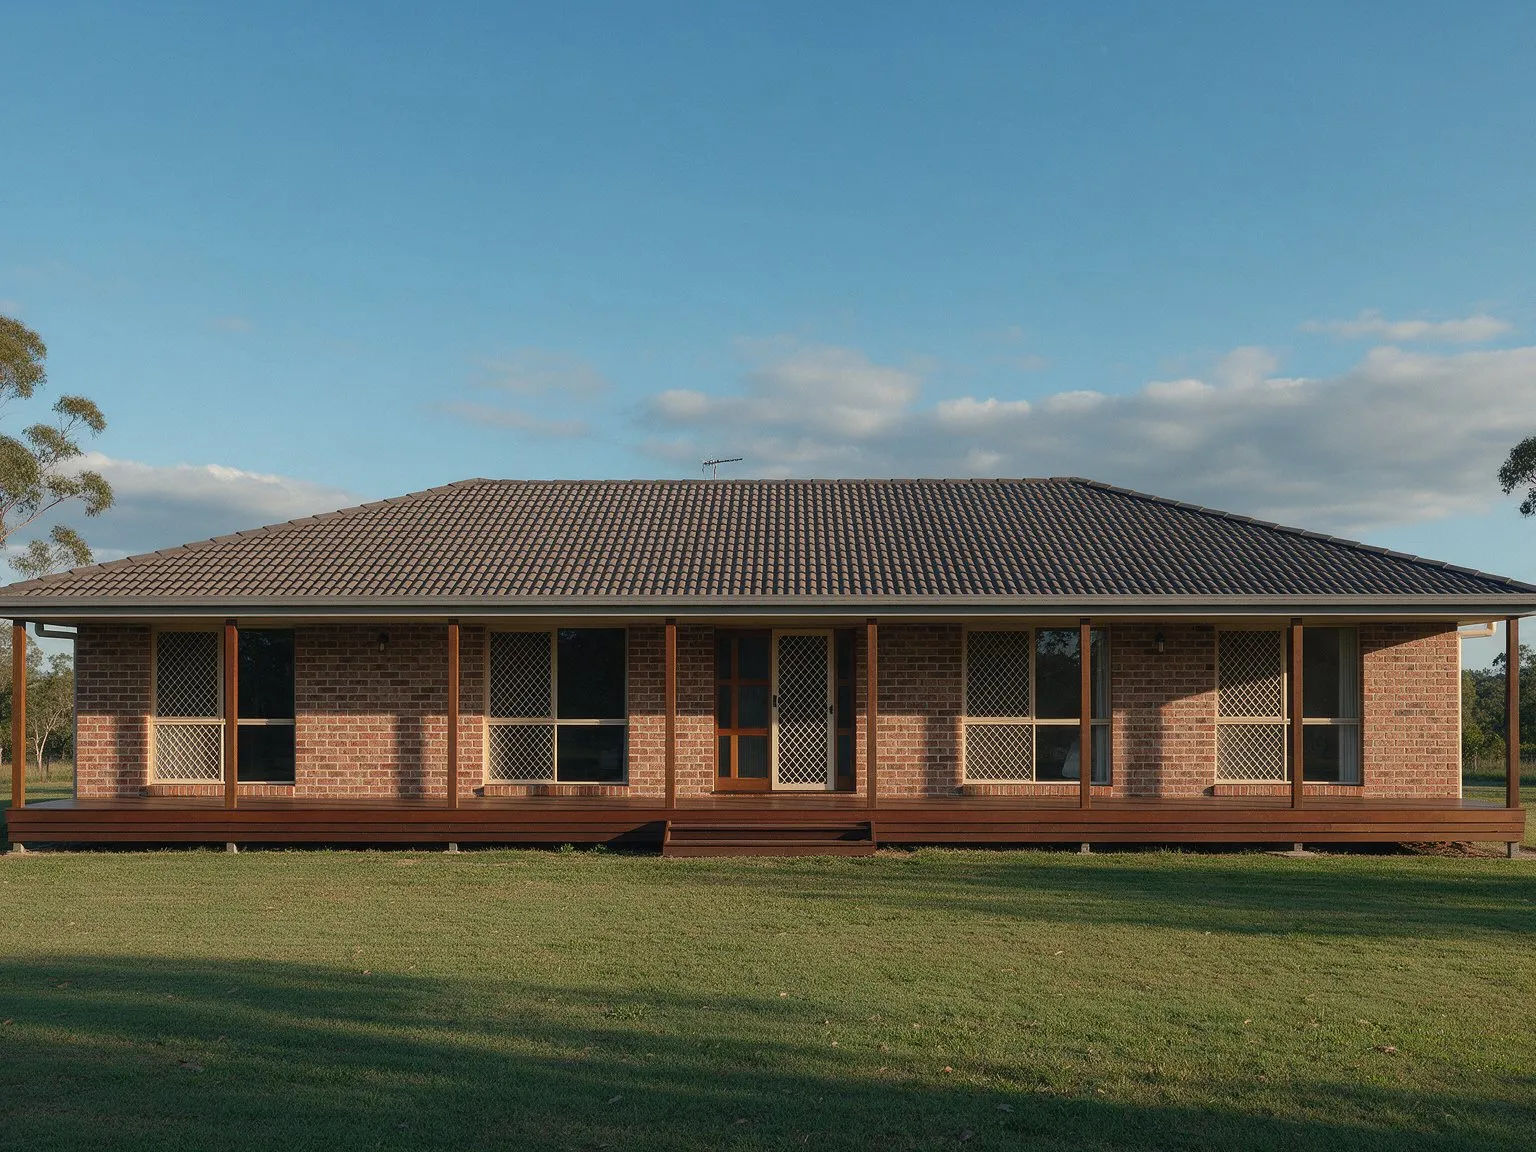
Representative image: a single-storey brick home with a timber verandah on a large rural-residential block in the Queensland hinterland

Second mortgage Funded October 2026

Yandina, QLD · regional residential security

Refinance business cash-flow debts

Property
Rural-residential home on acreage
Property value
$1,150,000
First mortgage ahead of us
$430,000
Amount we funded
$300,000
Combined LVR
63.5%
Term
6 months, open term
Borrower
Company run by two directors

Why they came to us

Two cash-flow lenders had said no because the business's last few months of bank statements looked thin. The directors owned their home with plenty of equity. We registered a second mortgage behind the existing bank loan, left that loan exactly where it was, and capitalised the interest for the term so nothing was payable while the business recovered.

Representative image. Location, property and figures changed.
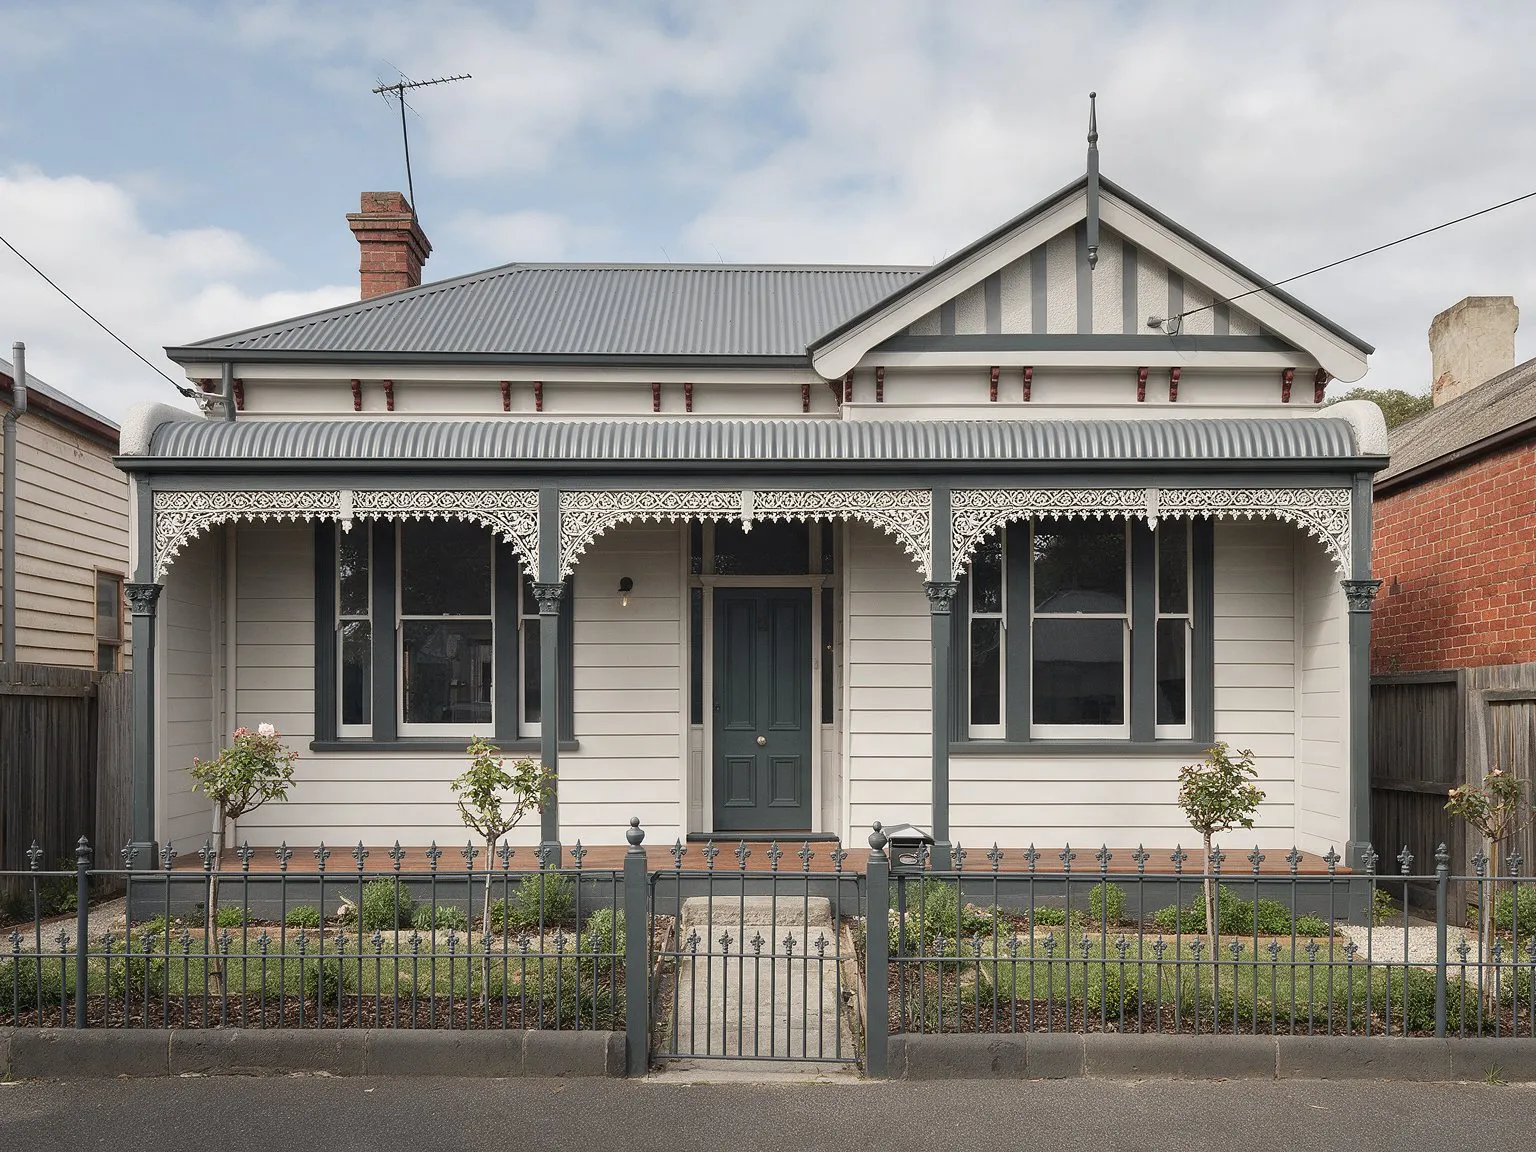
Representative image: a renovated Victorian-era weatherboard house with an iron-lace verandah in an inner-Melbourne street

First mortgage Funded October 2026

Brunswick, VIC · metro residential security

Pay out a lender in arrears and an ATO payment plan

Property
Company-owned investment house
Property value
$1,350,000
Paid out by our loan
$620,000
Amount we funded
$700,000
Combined LVR
51.9%
Term
12 months, open term
Borrower
Trading company

Why they came to us

A non-bank lender had issued default notices over the property and the company had fallen behind on an ATO payment plan at the same time. One first mortgage paid out the arrears loan and the ATO balance in a single settlement, so two pressures became one lender and one repayment plan, with a refinance to a bank as the exit.

Representative image. Location, property and figures changed.
Funded in September 2026

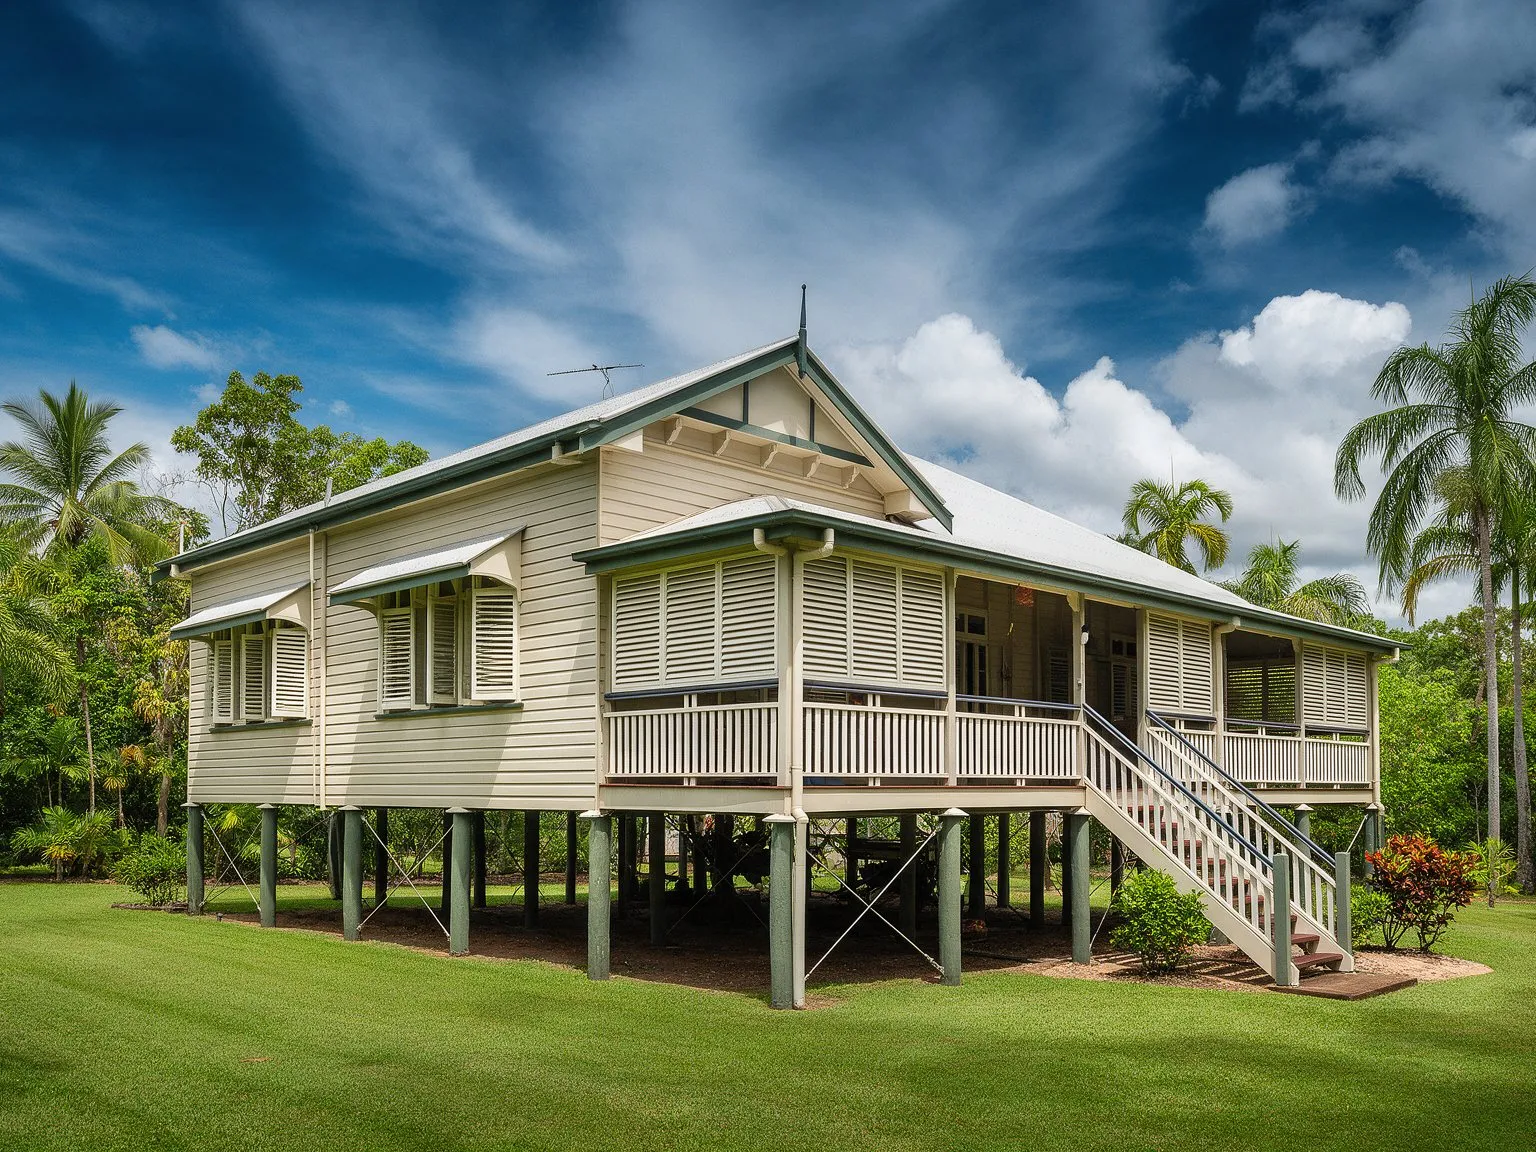
Representative image: an elevated tropical home with louvres and a wide veranda in a Darwin garden

Second mortgage Funded September 2026

Palmerston, NT · metro residential security

Stock and staffing ahead of the peak trading season

Property
Elevated tropical home
Property value
$980,000
First mortgage ahead of us
$380,000
Amount we funded
$200,000
Combined LVR
59.2%
Term
6 months, open term
Borrower
Hospitality company

Why they came to us

The owner of a hospitality business needed stock and staff in place before the dry-season peak, and the bank's overdraft review was weeks away. A second mortgage behind the existing home loan put the working capital in hand before the season opened, and the sale of the season's trade was the plan for repaying it.

Representative image. Location, property and figures changed.
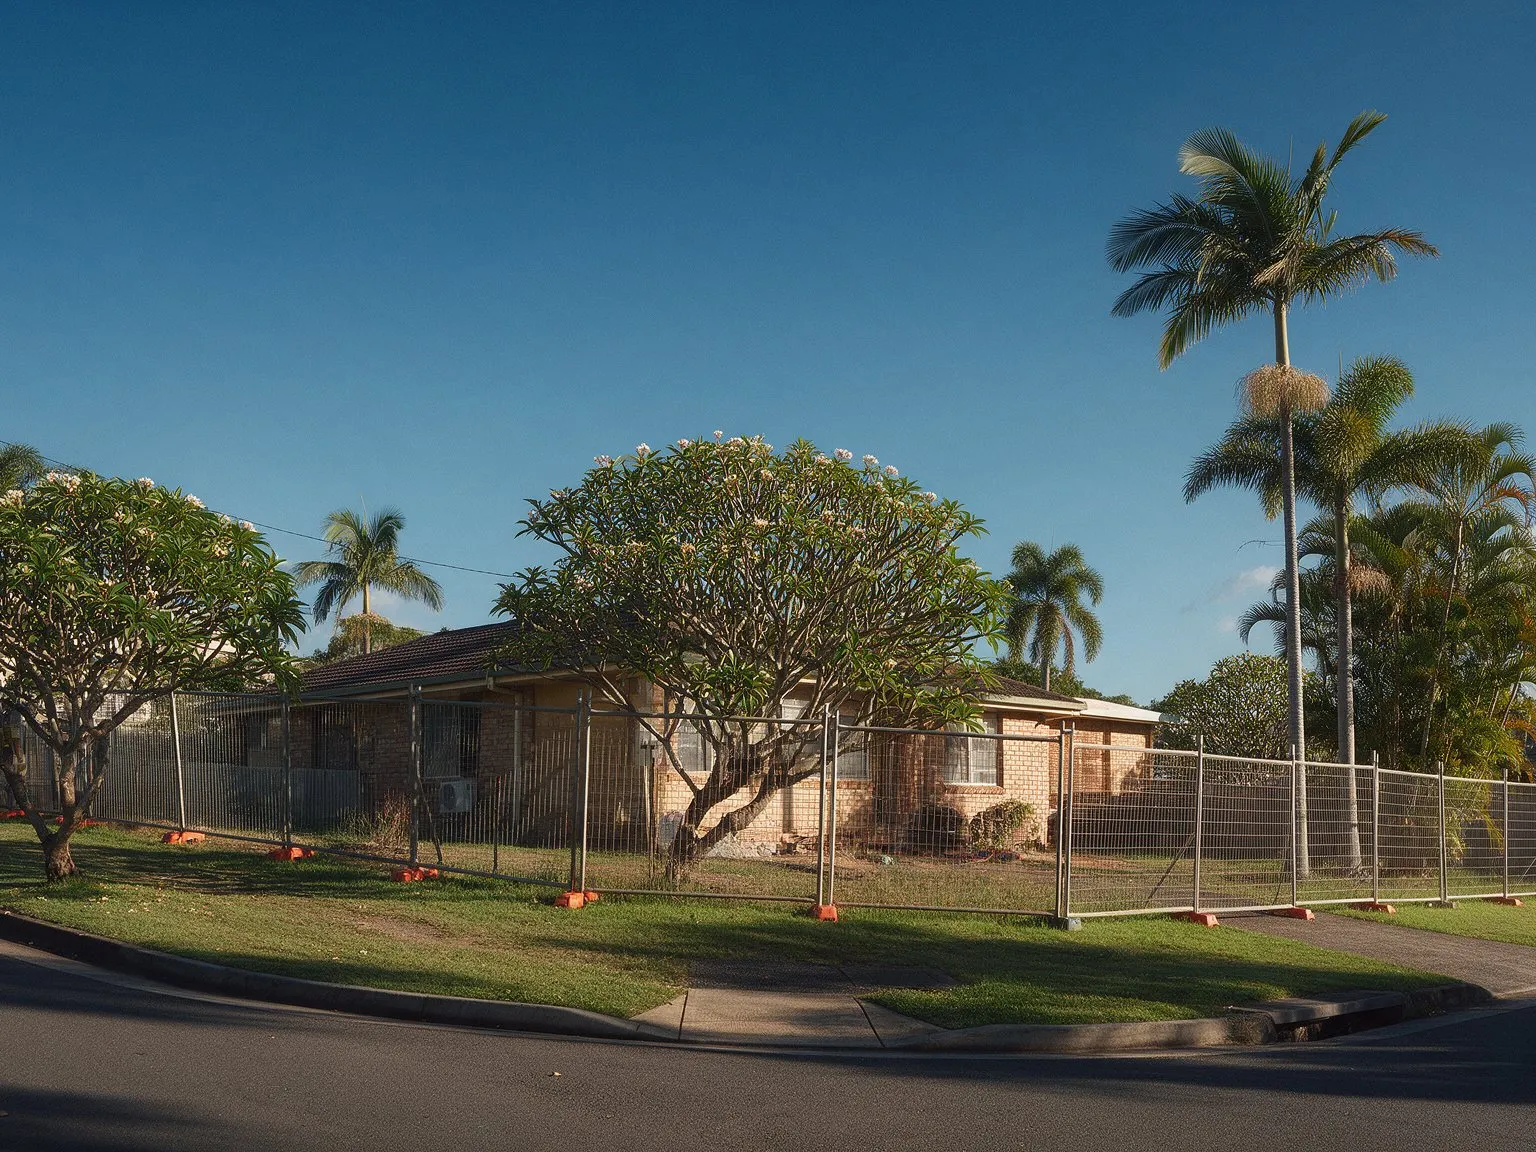
Representative image: an older low-set brick house on a wide corner block with temporary fencing in a Brisbane suburb

First mortgage Funded September 2026

Nundah, QLD · metro residential security

Purchase of a development site

Property
Development site, older house on a corner block
Property value
$1,850,000
Paid out by our loan
Nothing owing
Amount we funded
$1,110,000
Combined LVR
60%
Term
6 months, open term
Borrower
Property development company

Why they came to us

A property development company bought a corner site in its own name and needed to settle before another buyer could. A short-term first mortgage over the site let it settle on the contract date. The plan was to sell the site with approvals in place or refinance to a construction lender; HomeSec does not fund construction, and the loan did not.

Representative image. Location, property and figures changed.
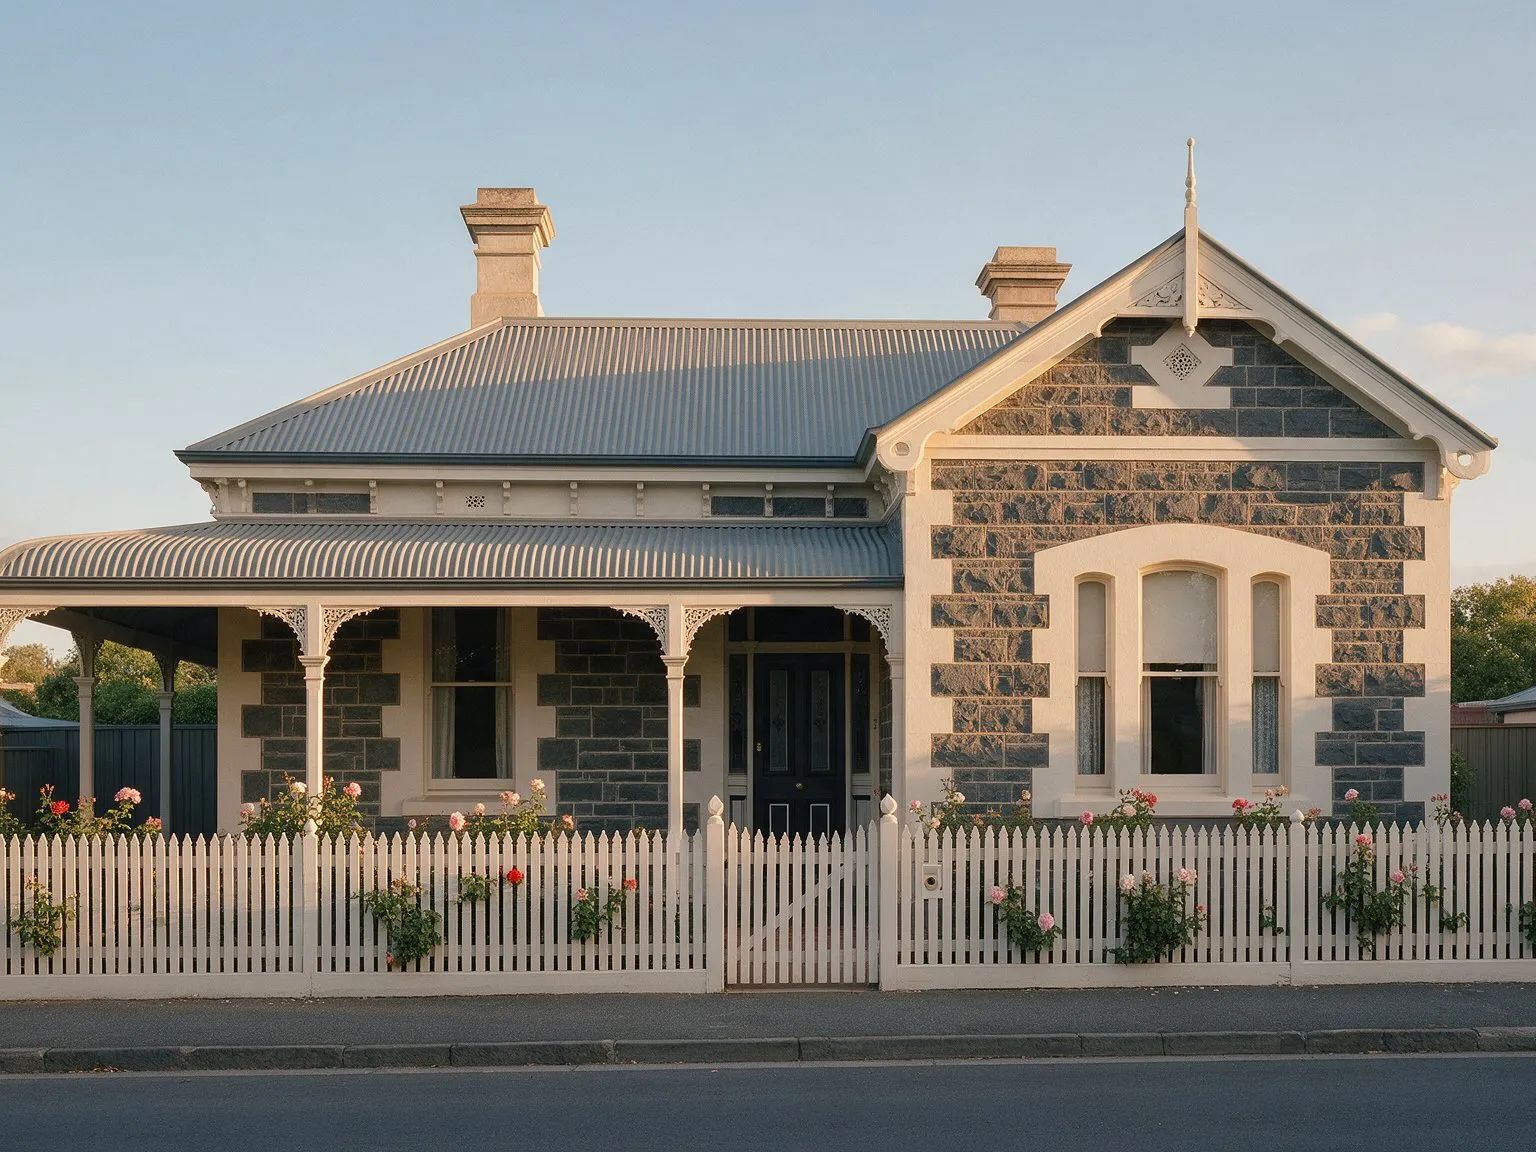
Representative image: a bluestone-fronted Adelaide villa with a return verandah and a white picket fence

Second mortgage Funded September 2026

Prospect, SA · metro residential security

Pay out a merchant cash advance and fund truck repairs

Property
Character villa
Property value
$850,000
First mortgage ahead of us
$300,000
Amount we funded
$150,000
Combined LVR
52.9%
Term
6 months, open term
Borrower
Transport company

Why they came to us

Daily direct debits from a merchant cash advance were taking most of a transport company's takings, and a truck was off the road waiting on repairs. A second mortgage paid out the advance and the repair bill, and capitalised interest meant no daily debit, and no weekly one, replaced it.

Representative image. Location, property and figures changed.
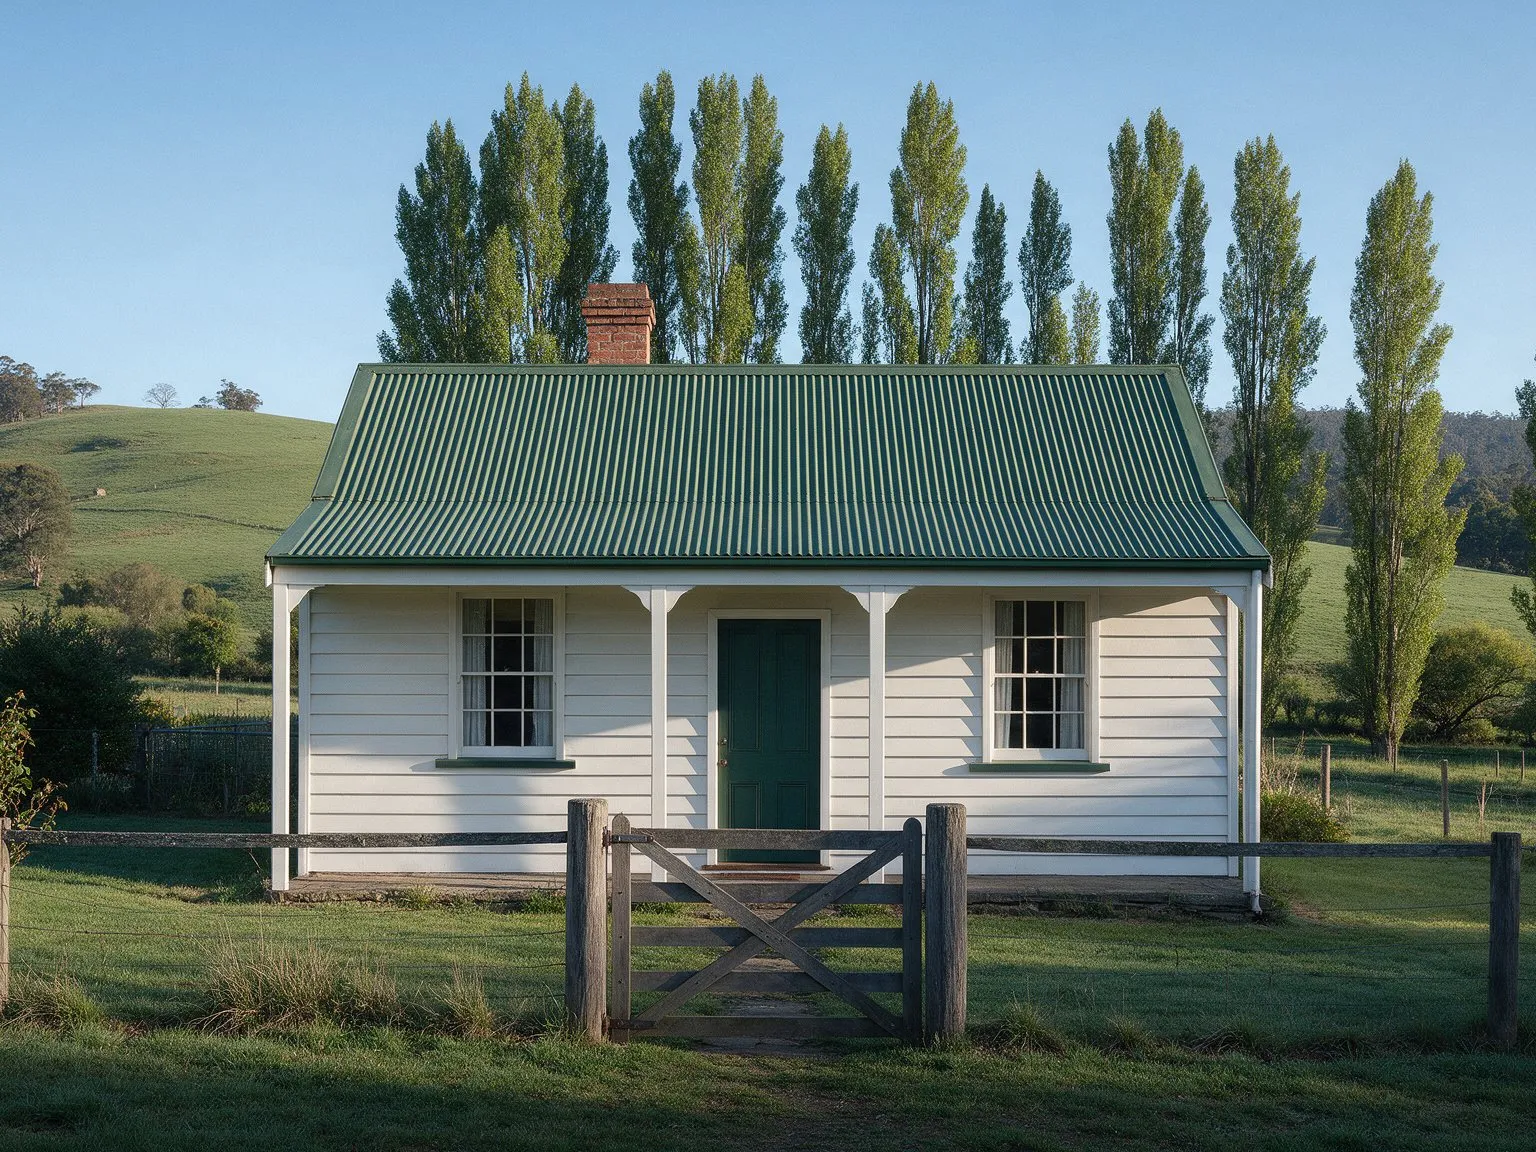
Representative image: a white weatherboard cottage with a green iron roof beside rolling hills near Launceston

First mortgage Funded September 2026

Newstead, TAS · regional residential security

Refinance an expiring private loan and release equity for stock

Property
Cottage on a freehold block
Property value
$720,000
Paid out by our loan
$410,000
Amount we funded
$450,000
Combined LVR
62.5%
Term
12 months, open term
Borrower
Family investment company

Why they came to us

A family investment company's private loan was about to expire and its lender would not roll it. A first mortgage paid out the expiring loan and released a little equity for stock, on an open term so the refinance to a bank could take the time it needed rather than a date set by the lender.

Representative image. Location, property and figures changed.
Funded in August 2026

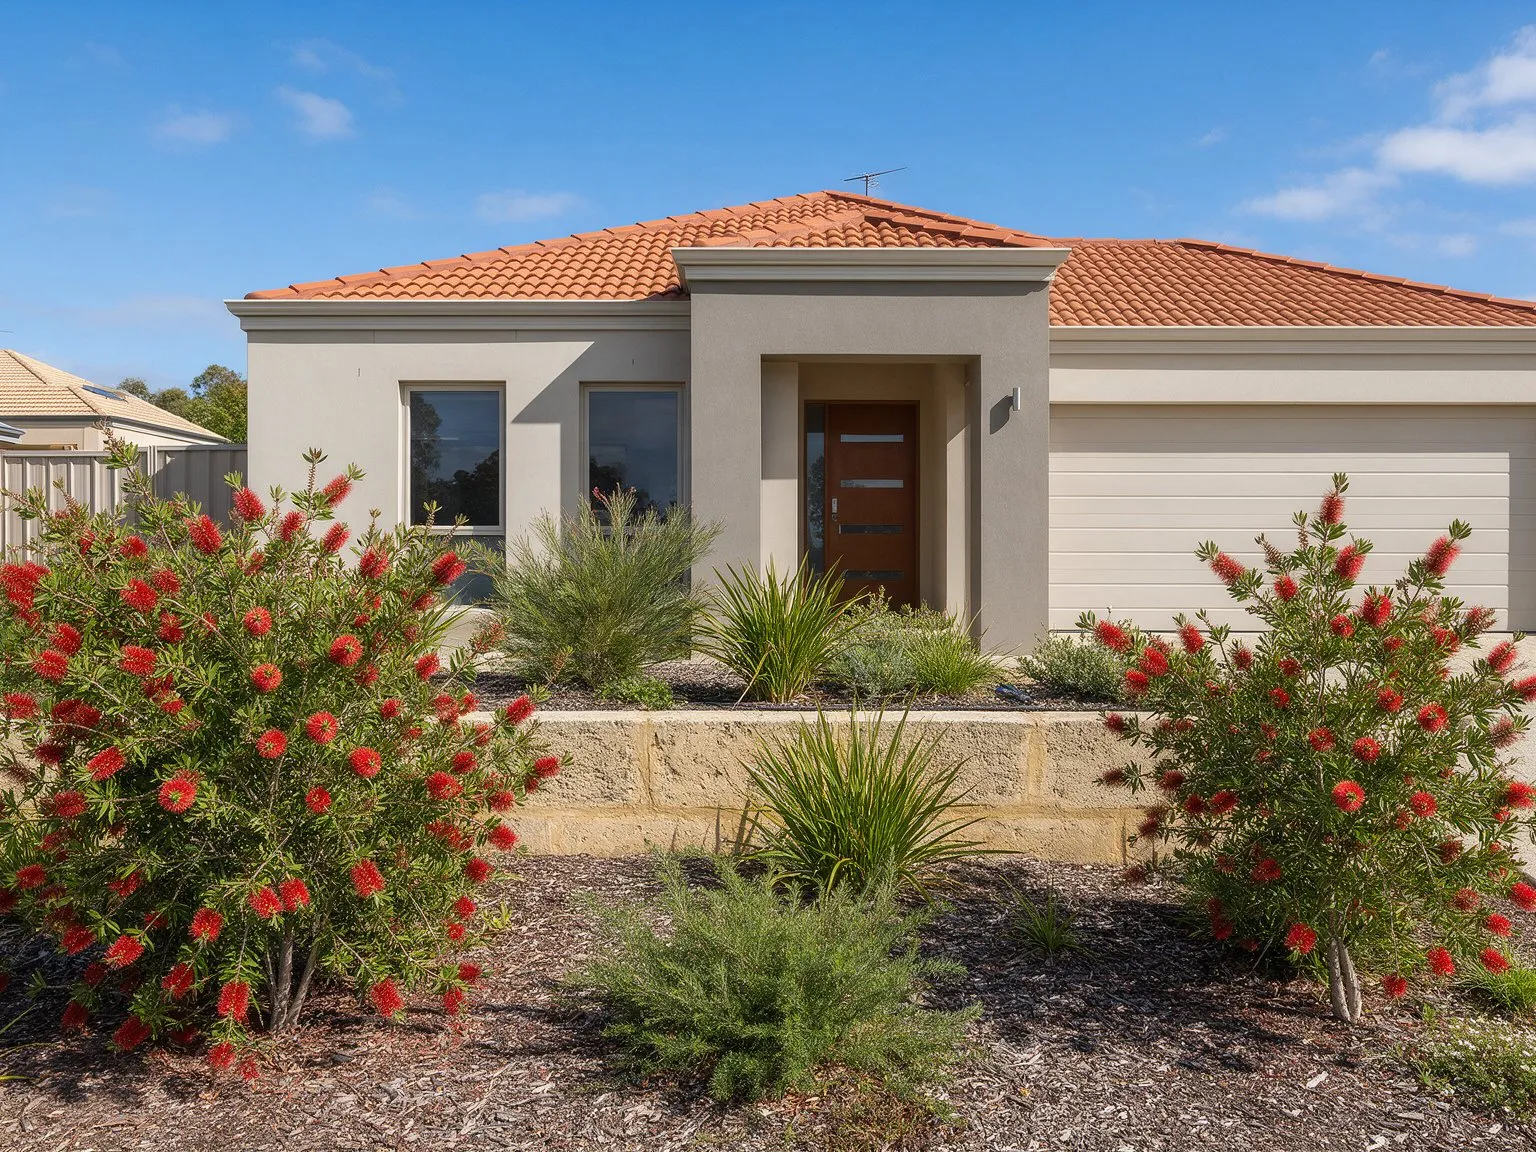
Representative image: a modern rendered home with a terracotta roof and native garden in a Perth suburb

Second mortgage Funded August 2026

Bayswater, WA · metro residential security

Equipment and mobilisation costs for a new contract

Property
Modern rendered home
Property value
$1,200,000
First mortgage ahead of us
$500,000
Amount we funded
$250,000
Combined LVR
62.5%
Term
12 months, open term
Borrower
Testing and engineering services company

Why they came to us

A services company won a larger contract than it had ever carried and needed equipment and mobilisation costs paid up front, months before the first progress payment. Its bank wanted a full credit review. A second mortgage funded the start-up costs while the contract's first invoices were still being raised.

Representative image. Location, property and figures changed.
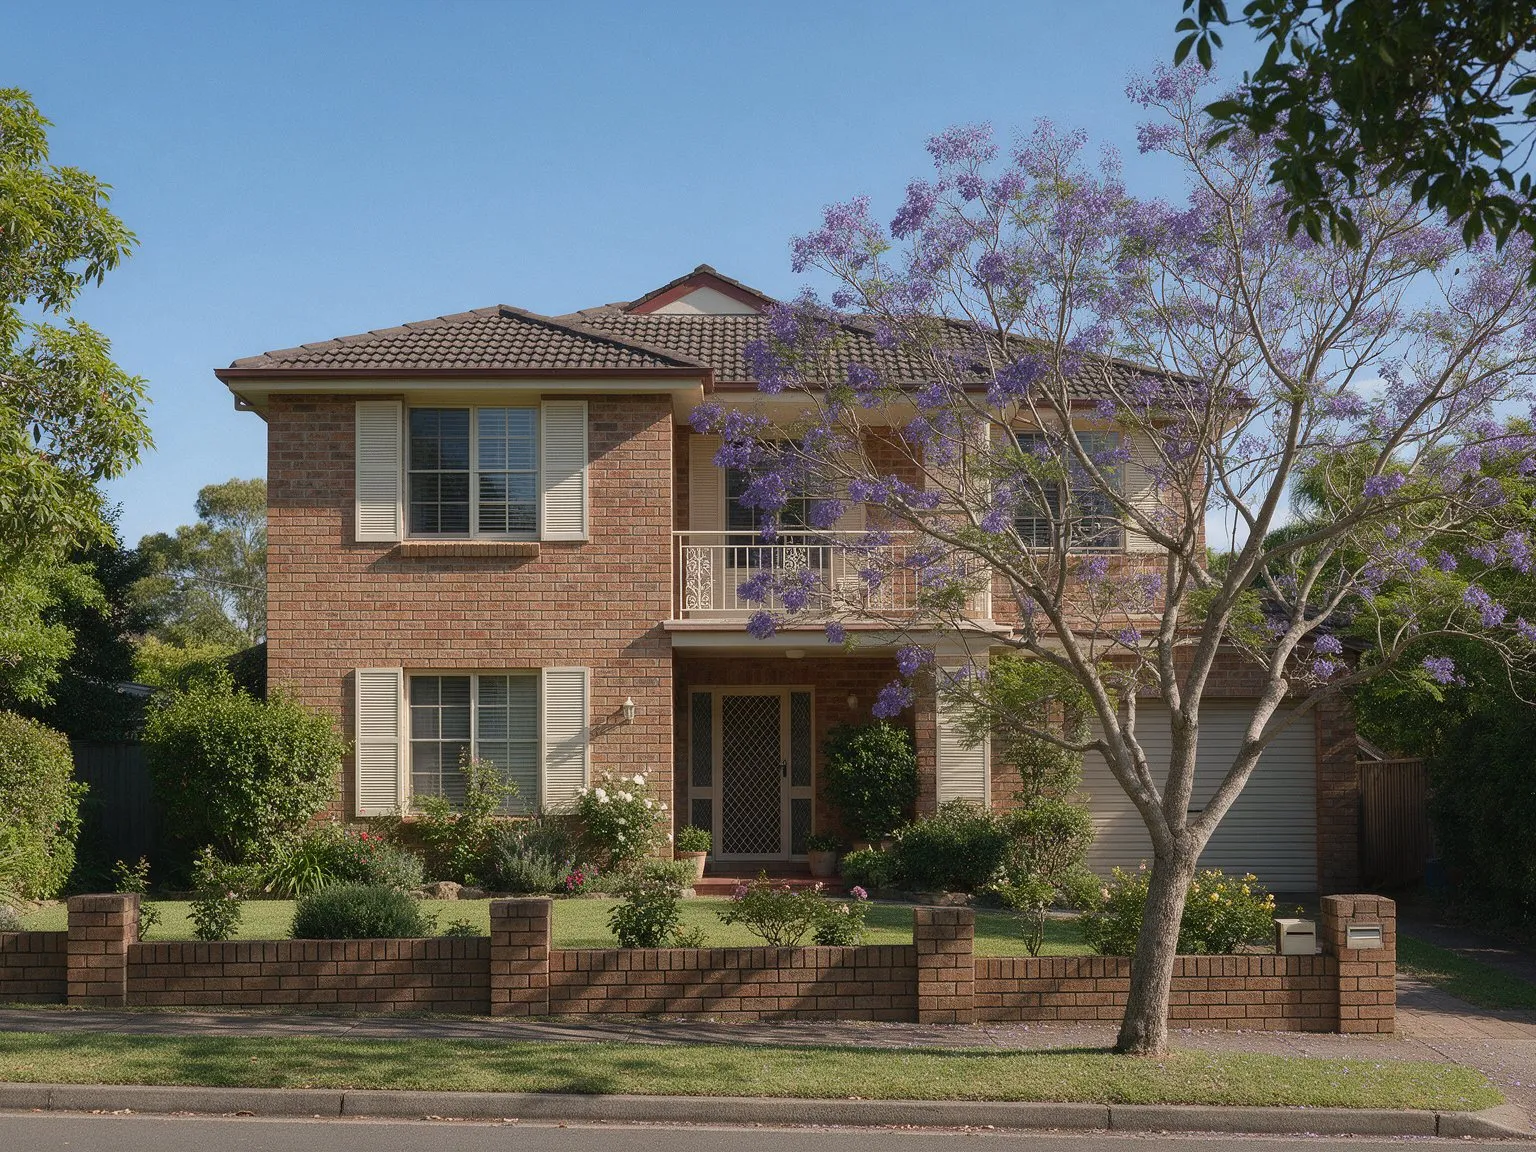
Representative image: a two-storey brick family home with a jacaranda tree in a leafy suburban street

Second mortgage Funded August 2026

Kaleen, ACT · metro residential security

Catch up payroll and superannuation

Property
Two-storey brick home
Property value
$1,600,000
First mortgage ahead of us
$600,000
Amount we funded
$350,000
Combined LVR
59.4%
Term
6 months, open term
Borrower
Contract services company

Why they came to us

A contract services business had lost a customer who owed it money and fallen behind on payroll and superannuation. A second mortgage brought both up to date within days, with interest capitalised for the term so the business had room to replace the lost revenue before repayment began.

Representative image. Location, property and figures changed.
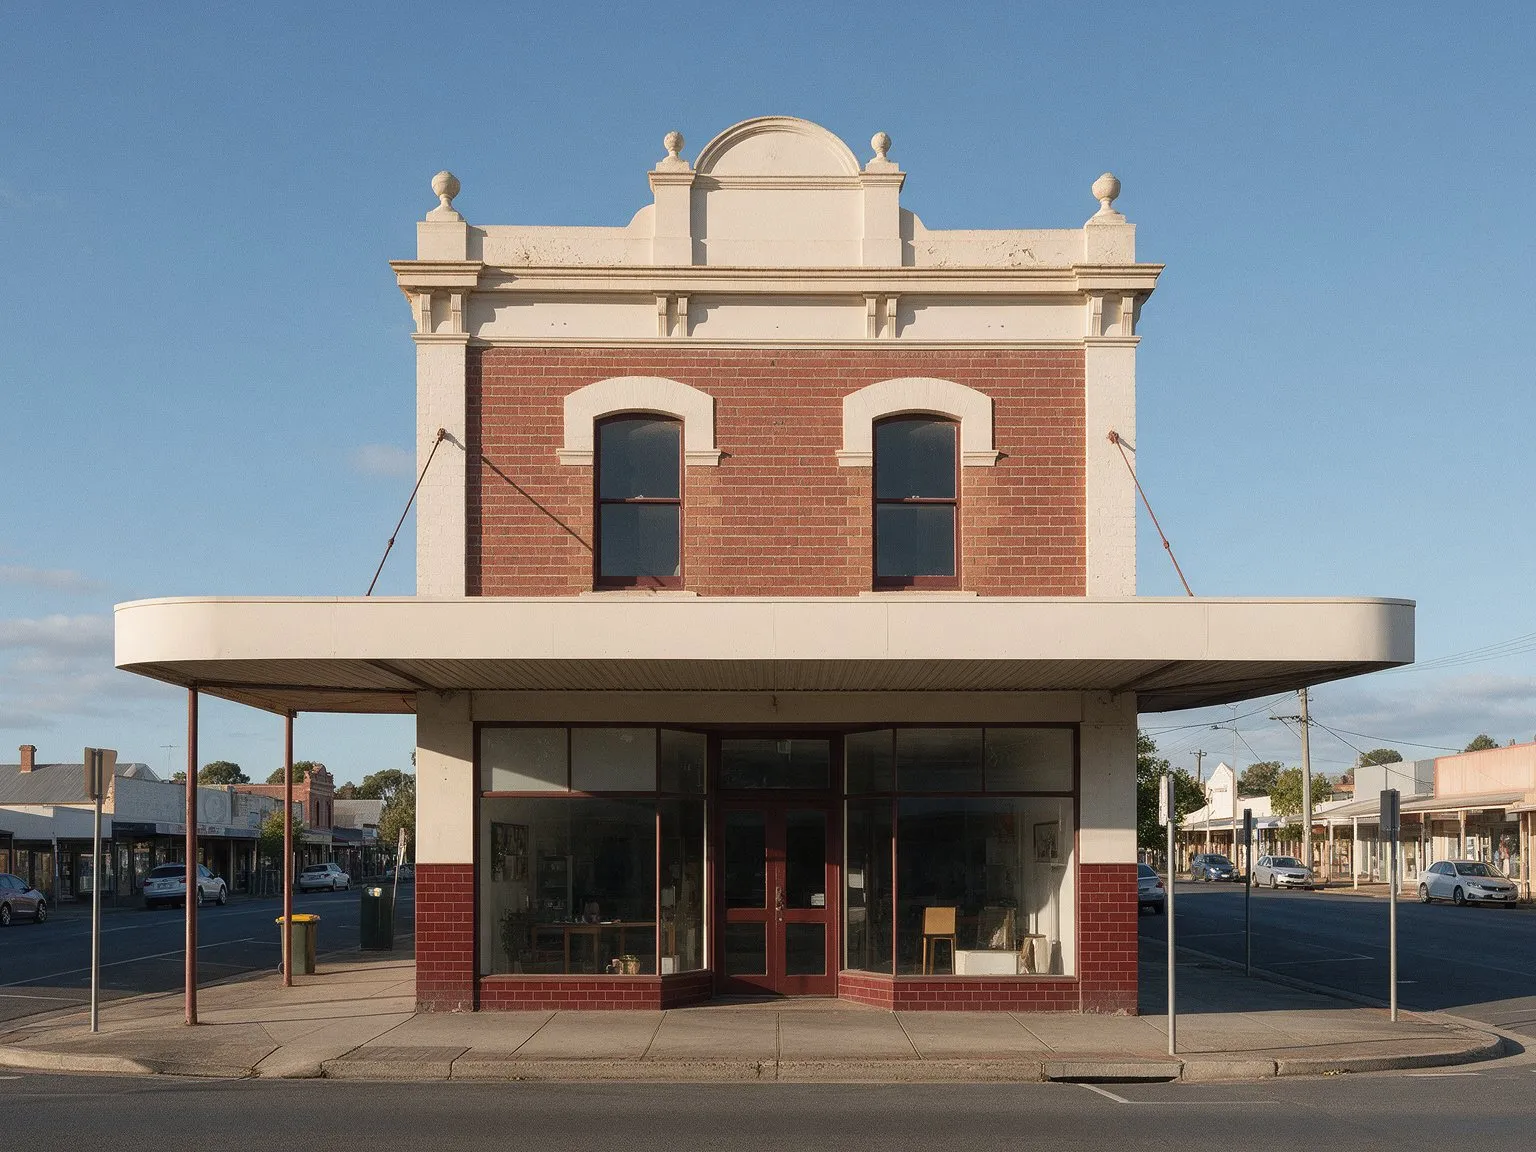
Representative image: a two-storey brick commercial building with a shopfront and awning on a regional Victorian main street

First mortgage Funded August 2026

Kangaroo Flat, VIC · regional commercial security

Refinance a facility the bank called in

Property
Two-storey shopfront on a main street
Property value
$1,100,000
Paid out by our loan
$390,000
Amount we funded
$660,000
Combined LVR
60%
Term
12 months, open term
Borrower
Hospitality operator

Why they came to us

A bank called in a hospitality operator's facility over a covenant breach even though trading was sound. A first mortgage over the shopfront the operator owned paid the bank out inside the notice period, at a commercial LVR well under our 70% ceiling, and the business kept trading without a break.

Representative image. Location, property and figures changed.
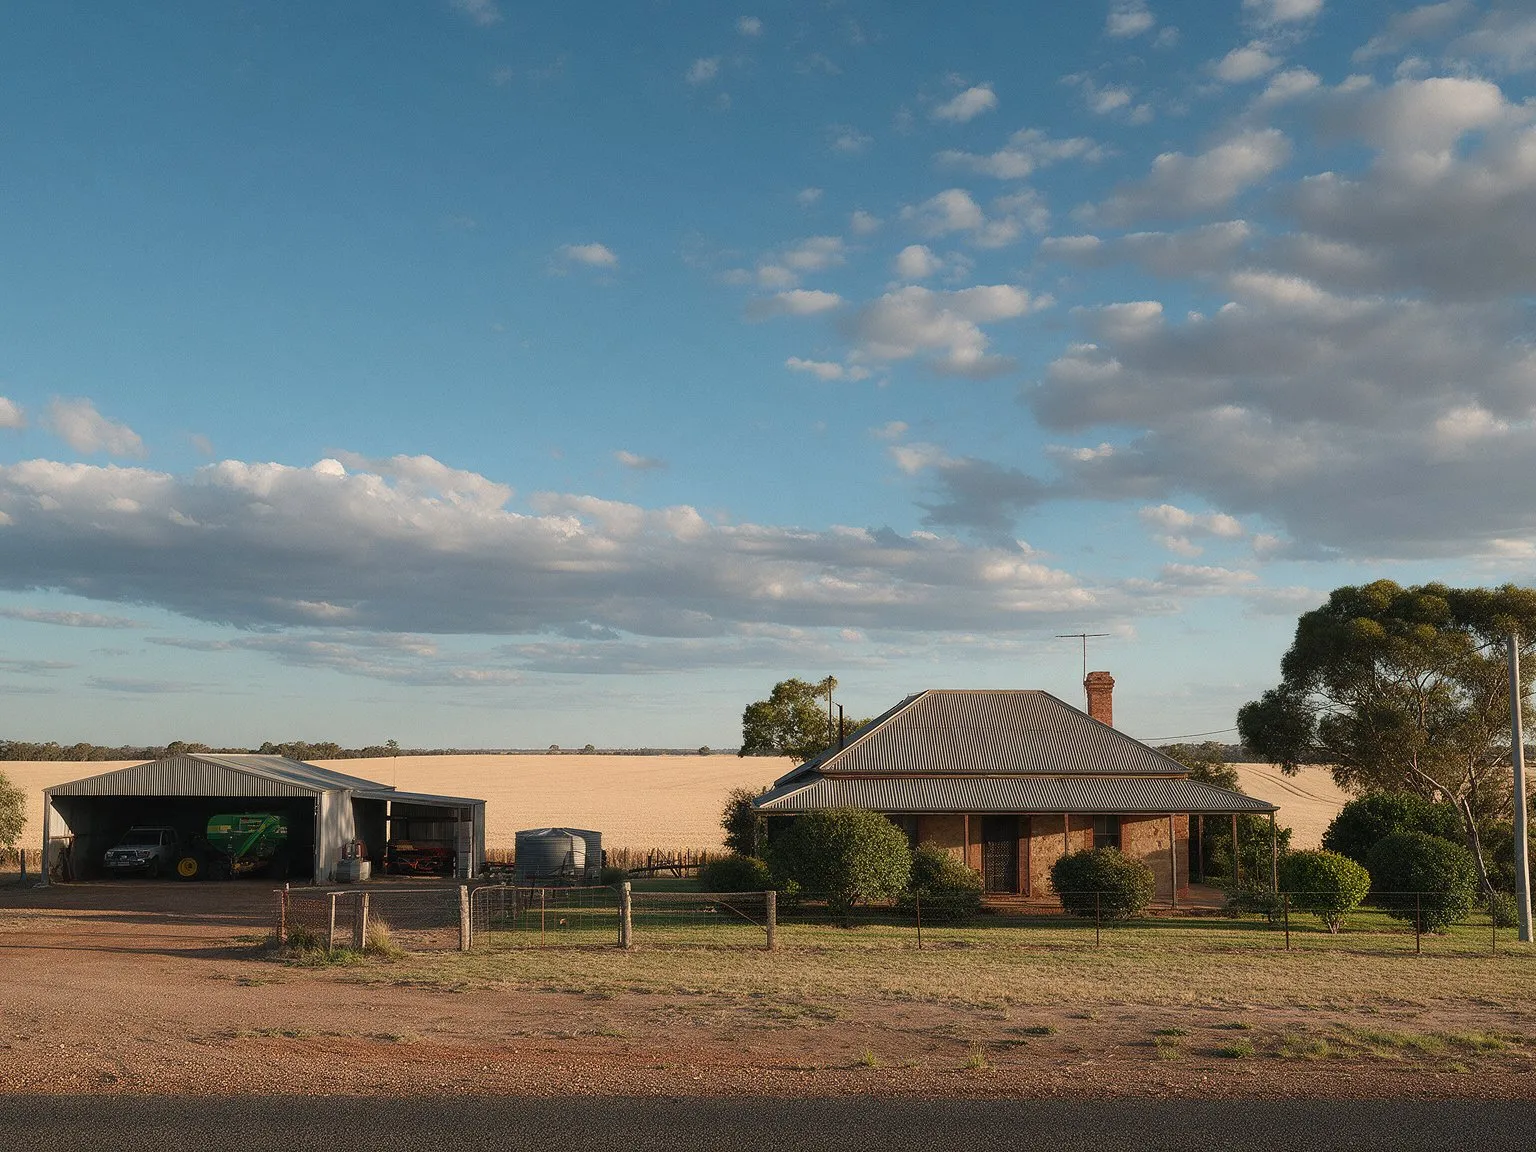
Representative image: a farmhouse and machinery shed beside wheat paddocks in central-west New South Wales

First mortgage Funded August 2026

Forbes, NSW · regional commercial security

Machinery purchase and seasonal working capital

Property
Farm with machinery shed
Property value
$2,900,000
Paid out by our loan
Nothing owing
Amount we funded
$1,450,000
Combined LVR
50%
Term
12 months, open term
Borrower
Farming company

Why they came to us

A farming company needed machinery and seasonal working capital before the harvest, owned its land outright and had no debt against it. A first mortgage at half the land's value put the money in hand in time, on an open term so the harvest, not a date on a calendar, decided when it was repaid.

Representative image. Location, property and figures changed.

What is a second mortgage?

A second mortgage is a loan secured by a registered mortgage over a property that already has a first mortgage on it. It ranks behind the first lender, and it lets an owner borrow against equity they already hold without paying out, refinancing or disturbing the existing loan. That is why it is usually the quicker of the two instruments over a property that already carries a bank loan: the existing mortgage stays exactly where it is, and the timetable is not set by the first lender's discharge. The usual range is 24 – 72 hours, with the first lender's consent the step that moves it. The full mechanics are on the second mortgage page, and the speed argument is on fast second mortgages.

The combined LVR in each example is the first mortgage balance plus our loan, divided by the property's value. It goes to 80% on residential security and 70% on commercial, and every example sits inside those limits.

What is a short-term first mortgage?

A first mortgage ranks ahead of any other lender over the property. A short-term first mortgage is one taken for months rather than decades: to settle a purchase on the contract date, to pay out a lender that will not roll its loan, or to replace several debts with one while the business recovers. HomeSec's first mortgages are open term, so you choose the term and there is no penalty for repaying early. Over a property with nothing owing, a first mortgage is as fast as a second. See first mortgage business loans for how it works, and business bridging loans where the loan is bridging a sale or a settlement.

Why business owners come for a first or second mortgage

A bank or cash-flow lender said no

Cash-flow lenders look at turnover and recent bank statements. When those are thin, the answer is no. A lender who looks at the equity in the property asks a different question. See declined by a cash-flow lender.

A deadline the bank will not meet

A settlement, a payroll, an ATO date or a supplier on stop supply. A second mortgage leaves the existing loan alone, so the date is not in the first lender's hands. See urgent business funding.

Debts that need to become one

A merchant cash advance with daily debits, an ATO payment plan and an arrears loan can be paid out together, with no daily or weekly direct debits afterwards. See business debt consolidation.

A purchase that has to settle

A developer or investor buying in a company name needs the money on the contract date, and the exit is a sale or a refinance. See buying a business and commercial loans.

How a first or second mortgage works with us

Step 1

Tell us the property and the purpose

Three short questions on the application, with no credit check to apply and no financial statements.

Step 2

We look at the equity, the purpose and the exit

A Lending Manager reads it and calls you. The property, not turnover, is the test.

Step 3

You choose how repayments work

Interest-only, or interest capitalised for up to six months so nothing is payable at first.

Step 4

We settle

As little as 24 hours from a clean, complete scenario. Every application is subject to assessment and approval.

Figures are rounded and changed. Examples are updated monthly; the list of loans on this page is not a list of loans available to everyone. Not an offer or advice, and subject to assessment and approval.

Questions about first and second mortgages

What is a second mortgage?
A second mortgage is a loan secured by a registered mortgage over a property that already has a first mortgage on it. It ranks behind the first lender, so the first lender is repaid first if the property is ever sold, and it lets an owner borrow against the equity they already hold without paying out or disturbing the existing loan. HomeSec lends from $20,000 to $5,000,000 against property in this way.
What is a short-term first mortgage?
A first mortgage is a loan that ranks ahead of any other lender over the property. A short-term first mortgage is one taken for months rather than decades, usually to bridge a gap: a purchase that has to settle, an existing lender that will not roll its loan, or a debt that has to be paid out quickly. HomeSec's first mortgages are open term, so the term is the one you choose and there is no penalty for repaying early.
Are these real loans?
Each example is modelled on a loan we settled in the month shown. To protect our clients we change the suburb, the property and the figures, so no one can be identified, and the photograph is a representative image rather than the actual property. They show the kinds of loan we fund and why people come to us; they are not a promise that your loan would be funded on the same terms.
How much equity do I need for a second mortgage?
Enough that the combined loans stay inside our limits: up to 80% of the property's value on residential security and 70% on commercial. The combined LVR is the first mortgage balance plus what we lend, divided by the property value. Every example above shows its combined LVR so you can see how much room was left.
Do you lend outside the capital cities?
Yes, anywhere in Australia. The examples on this page include regional Queensland, Tasmania, regional Victoria and rural New South Wales alongside Melbourne, Brisbane, Adelaide, Perth, Canberra and Darwin. What matters is the equity in the property and the business purpose, not the postcode.
Do you fund construction, or loans to buy a home to live in?
No. HomeSec does not fund construction, and it does not lend to buy or refinance a home someone will live in. Loans are for business and investment purposes. Where an example involves a purchase, the buyer is a company that is a developer or investor, and the loan is for the site or the building as it stands.
How fast can a second mortgage be funded?
As little as 24 hours from a clean, complete scenario, and the usual range is 24 – 72 hours. The difference between the two ends is usually the first lender's consent. The page on fast second mortgages explains where the time goes. Every application is subject to assessment and approval.
Can I get a second mortgage with bad credit or no financials?
Often, yes. We assess the equity in the property, the business purpose and the exit rather than a credit score or recent financial statements, which is why several examples above came to us after a bank or a cash-flow lender had said no. See second mortgages with bad credit and no doc business loans.
Sixty seconds, no documents

See if you qualify in sixty seconds

Three short questions, no credit check to apply and no financial statements. A Lending Manager reads it and calls you back with a real answer — not a call centre, not an algorithm.

That's the HomeSec Advantage.

See if you qualify Call 1300 93 83 87 Mon–Fri, 8:30am – 5:30pm Melbourne time

Reviewed by Jason Brockmuller, Joint Chief Executive

1300 93 83 87 homesec.com.au
Get funded Call 1300 93 83 87

Before you go — $20,000 to $5,000,000 against property equity

Business funds can be available in as little as 24 hours — with no payments for up to 6 months.

First and second mortgages. No financials, no cashflow records and no sworn valuation needed. Every application is subject to assessment and approval.

See if you qualify

Or talk to a Lending Manager on 1300 93 83 87, Mon–Fri, 8:30am – 5:30pm Melbourne time.